
The target implies a potential upside of 15.75% from the stock’s last closing level on Monday.
Morgan Stanley expects accelerating thermal power demand, sharply de-stocked plant inventories and rising global thermal coal prices to support volume growth and e-auction premium expansion.
These factors should drive strong earnings upgrades and, in turn, support stock performance over the next few months, according to the brokerage.
Morgan Stanley has revised its volume and e-auction premium estimates, resulting in a 20% upgrade to its FY27 EPS estimate.
At 6.6x one-year-forward P/E, Coal India’s stock is trading around its long-term average. Morgan Stanley expects this multiple to sustain on the back of strong earnings upgrades.
Earlier this month, Coal India shared its provisional business update for August.
Coal India’s production for August declined 5.7% from last year to 47.5 MT. However, offtake increased 5.5% to 60.6 MT.On a year-to-date basis, Coal India’s production stood at 267.5 MT for the April-August period, down 4.5% from the corresponding period last year. Coal India has set its FY27 production target at 815 MT.
Dispatches during the April-August period increased 6.7% year-on-year to 322.9 MT.
Coal India’s e-auction premium indicated a 59% growth from the comparable period. For the April-August 2026 period, e-auction premiums are up 46%, compared with 35% during April-August 2025.
Of the 26 analysts covering Coal India, 16 have a ‘Buy’ rating, while five each have a ‘Hold’ and a ‘Sell’ call on the stock.
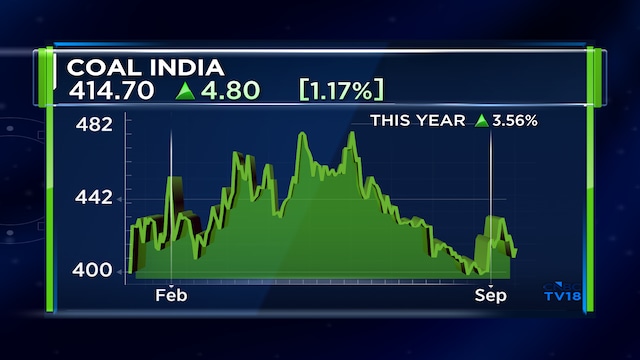
Shares of Coal India ended 1.17% higher on Monday at ₹414.70. The stock is up 4% so far this year.