
Nuvama has maintained its “hold” rating on Dixon Technologies, with a target price of ₹14,800 per share, which is indicating an upside potential of 10.9% from its previous closing price.
The brokerage said it is cutting Dixon’s EPS estimates for the financial year 2027 by 7% on a likely delay in the Vivo JV consolidation, while it has raised its FY28 EPS estimates by 9% on faster scale up of the components vertical.
In its interaction with the management of Dixon Tech, Nuvama said that according to the company, the Dixon-Vivo JV commercialisation is likely to be in the third quarter of FY27 instead of October 2026, as was planned earlier. As a result of the delay in the Vivo consolidation, the second half of the year becomes weaker for Dixon than the first half.
Nuvama also highlighted the management’s views on the smartphone market, which, according to them, has been weak in the second quarter of this fiscal so far, declining 15%-20% from last year. However, Dixon Tech said it is likely to gain market share and reiterated its FY27 guidance of 33 million units, the brokerage added.
Dixon said export realisations are becoming difficult, making the company’s export volume and price-growth targets harder to achieve.
It added that the telecom and IT hardware segments continue to gain further traction. The revenue for telecom vertical in FY27 is anticipated at ₹6,500 crore to ₹7,000 crore, up 40% from last year, and for the IT Hardware segment to be at ₹6,000 crore, up 275% from the year-ago period.
A total of 33 analysts have coverage on Dixon Technologies, with 24 of them having “buy” recommendations, four having “hold” recommendations and five with “sell” ratings.
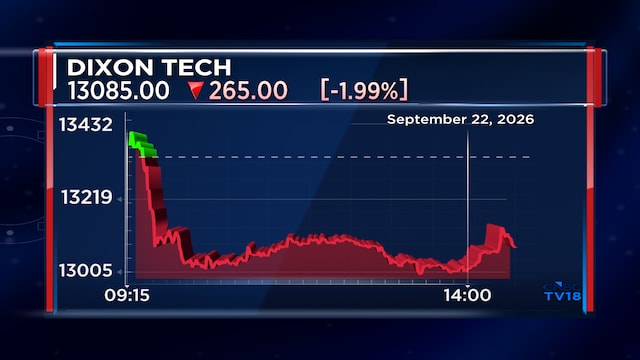
Shares of Dixon Tech are trading 2.1% lower on Tuesday at ₹13,070. The stock is down over 10% in the last one month and has gained 8% so far this year. In-line with Dixon, shares of other EMS companies such Kaynes Tech and PG Electroplast, are trading with losses between 3% to 4%.
Also Read: Lupin share price is currently ‘overemphasizing’ a risk while ‘undermining’ a positive, HSBC says