
JPMorgan retained its “overweight” rating on Dixon Techwith a target price of ₹16,400, implying around 25% upside from Tuesday’s close of ₹13,084.
The brokerage sees significant headroom for Dixon to scale as India looks to emerge as a global electronics manufacturing hub, while the company expands into components and higher-margin product categories.
India’s EMS opportunity
According to JPMorgan, India has the potential to become the next major electronics manufacturing hub given its relatively low share of the global EMS market. With global clients looking for alternative sources of labour, the brokerage expects India to benefit, creating a strong case for further investment in the country’s EMS sector.JPMorgan noted that Dixon already operates across multiple product categories and is also entering component manufacturing, providing scope to expand its business further.
Exports seen as the next growth driver
JPMorgan said India’s EMS industry has so far seen strong growth largely driven by domestic demand. However, the next phase of growth will need to come from exports.
For India to become more competitive in global markets, the country will need to address factors such as the cost of land and power while building a stronger component ecosystem, according to the brokerage.
Dixon eyes higher-margin segments
Dixon has historically operated with return on capital employed (ROCE) of more than 30% and remains conscious of maintaining those returns, JPMorgan said.
The brokerage does not expect the company’s move into component manufacturing to dilute its ROCE, citing government incentives under the Electronics Component Manufacturing Scheme (ECMS).
Dixon is also looking to move up the value chain by entering low-volume, high-margin segments such as defence, medical electronics, drones and robotics. The company is open to pursuing acquisitions as well as building these businesses organically, according to JPMorgan.
Street view and stock reaction
According to Bloomberg consensus data, 24 of 33 analysts covering Dixon Tech have a “buy” rating, while four have a “hold” rating and five have a “sell” recommendation. The 12-month consensus target price stands at ₹15,119, implying around 15% return potential from the stock’s last price of ₹13,181.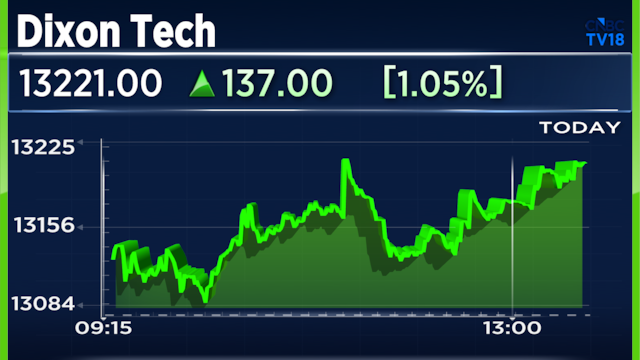
Shares of the company were trading nearly 1% up at ₹13,204 as of 1.30 pm on Wednesday. The stock has advanced more than 9% since the beginning of 2026, while declining over 27.2% in the trailing 12-month period.
Also read: Why Oil india’s ‘large’ valuation premium over ONGC appears ‘indefensible’ to Kotak