
Jefferies maintained its “buy” recommendation on Coal India with a target price of ₹500 per share.
The brokerage in its note said coal stocks at power plants have dropped to just seven days compared to the last 10-year average of 15 days. The power demand growth has accelerated from 1% in the financial year 2026 to 9% in April to August this year.
Jefferies estimates factor in a 5% compound annual growth rate in Coal India’s dispatch volumes over FY26-29.
The brokerage believes higher global coal prices should support e-auction prices. It has estimated the e-auction prices to be between ₹3,000 to ₹3,200 over financial year 2027-2029.
Jefferies believes that after Coal India’s Earnings Per Share (EPS) declined by 12% over financial year 2024-2026, it can improve by a 6% CAGR over financial year 2026-2029.
According to Jefferies, Coal India’s valuations are attractive at nine times the one-year forward adjusted price-to-earnings ratio and 7% dividend yield.
Coal India reported its first quarter earnings in July.
Its net profit increased 0.63% to ₹8,852 crore from ₹8,797 crore in the previous year.
The company’s revenue was up 7.8% in the June quarter at ₹46,254.8 crore from ₹42,919.2 crore last fiscal.
Its earnings before interest, taxes, depreciation and amortization (EBTIDA) declined 4.1% to ₹12,069 crore from ₹12,588 crore and margin contracted to 26.1% from 29.3% in the year-ago period.
It also declared an interim dividend of 5.5 per share for FY26-27.
A total of 26 analysts have coverage on the Coal India stock. Of them, 16 have a “buy” recommendation, while five have “hold” and “sell” ratings, each.
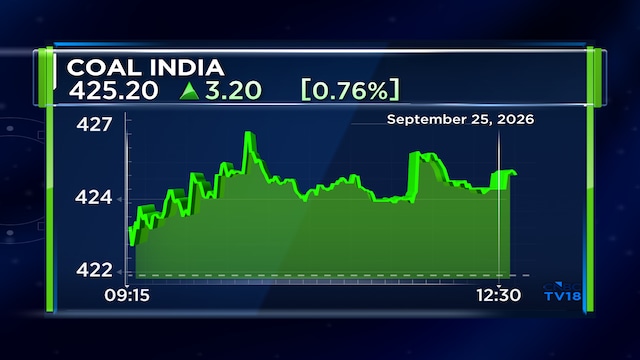
Shares of Coal India are trading 0.6% higher on Friday at ₹424.75. The stock is up 6% so far this year.
Also Read: Natco Pharma approves ₹1,279 crore rights issue – Check dates, price, entitlement ratio and more