
Bharat Electronics Ltd (BEL) remains a preferred pick in the defence sector for PL Capital, with the brokerage expecting growth to be supported by fresh order inflows, defence electronics demand and indigenous manufacturing.
PL Capital has a target price of ₹452 for the stock, implying an upside of around 26% from current levels.
Amit Anwani, Research Analyst at PL Capital, added, “For Bharat Electronics I am building in 14-15% topline growth this quarter, and roughly about 26.5% margin.”
Apart from its core defence business, BEL has exposure to non-defence segments, including cybersecurity, civil projects and electronic voting machines (EVMs). The company has also undertaken projects for the Delhi Metro Rail Corporation (DMRC).
However, PL Capital does not expect the non-defence business to contribute significantly more to the company’s overall revenue mix in the near term.
The non-defence business currently accounts for around 10–15% of BEL’s operations, and the brokerage expects it to grow steadily, potentially at around 15%.
The larger growth opportunity, however, lies in the defence business. New contracts for quick reaction surface-to-air missile (QRSAM) system, next-generation aircraft and naval platforms could strengthen BEL’s order pipeline and improve revenue visibility through FY31.
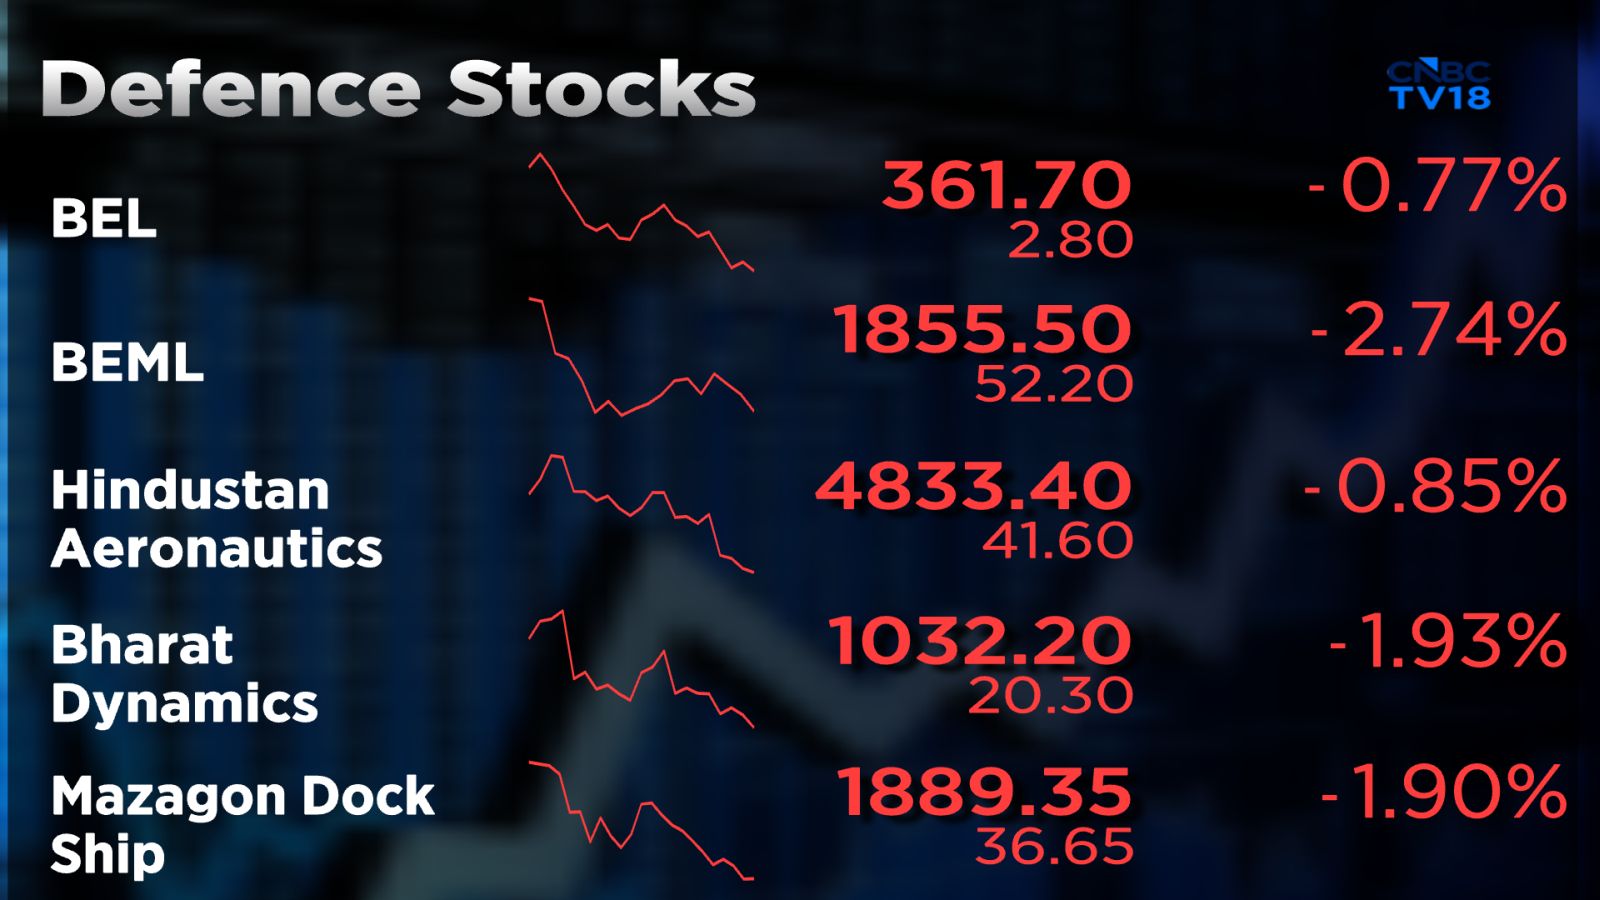
He expects companies in his defence coverage universe to report revenue growth of around 18-20% in the current quarter, although performance is likely to vary across companies and segments.
Solar Industries is expected to deliver particularly strong growth, with revenue projected to rise by more than 45%, supported by its international explosives business. Meanwhile, Hindustan Aeronautics Ltd (HAL) is expected to report revenue growth of 10–11%, with margins of around 27%.
The broader defence sector is expected to see healthy growth, particularly among companies operating in defence electronics. However, growth in the platform and shipbuilding segments could be more moderate, partly because of the timing of new orders.
Despite a correction in defence stocks from their recent highs, Anwani believes the sector’s longer-term growth prospects remain encouraging. However, the timing of fresh order inflows and the pace of execution will be important factors for investors to track.
Several defence stocks have declined significantly from their 52-week highs, reflecting concerns about order visibility and the timing of new contracts. According to Anwani, order inflows across the sector could be weighted towards the final quarter of the financial year, with several clearances potentially coming through in January, February and March.
BEL, for instance, had received orders worth around ₹9,000 crore against its guidance of ₹25,000 crore in order inflows for the year. The brokerage expects additional large orders to improve revenue visibility over the next two to three years.
The timing of these contracts remains important for companies that depend heavily on fresh orders to sustain growth. This is particularly relevant for shipbuilding companies, where order inflows have moderated and large contracts are awaited.
Anwani believes the current slowdown in order inflows could be temporary, given the substantial defence procurement announcements made over the past year and the government’s continued focus on strengthening domestic defence capabilities.
For full interview, watch accompanying video

Bharat Electronics remains top defence pick for PL Capital; sees order inflows picking up in Q4
Follow our live blog for more stock market updates
NOTE TO READERS
Disclaimer: The views and investment tips expressed by investment experts on CNBCTV18.com are their own and not that of the website or its management. CNBCTV18.com advises users to check with certified experts before taking any investment decisions.