
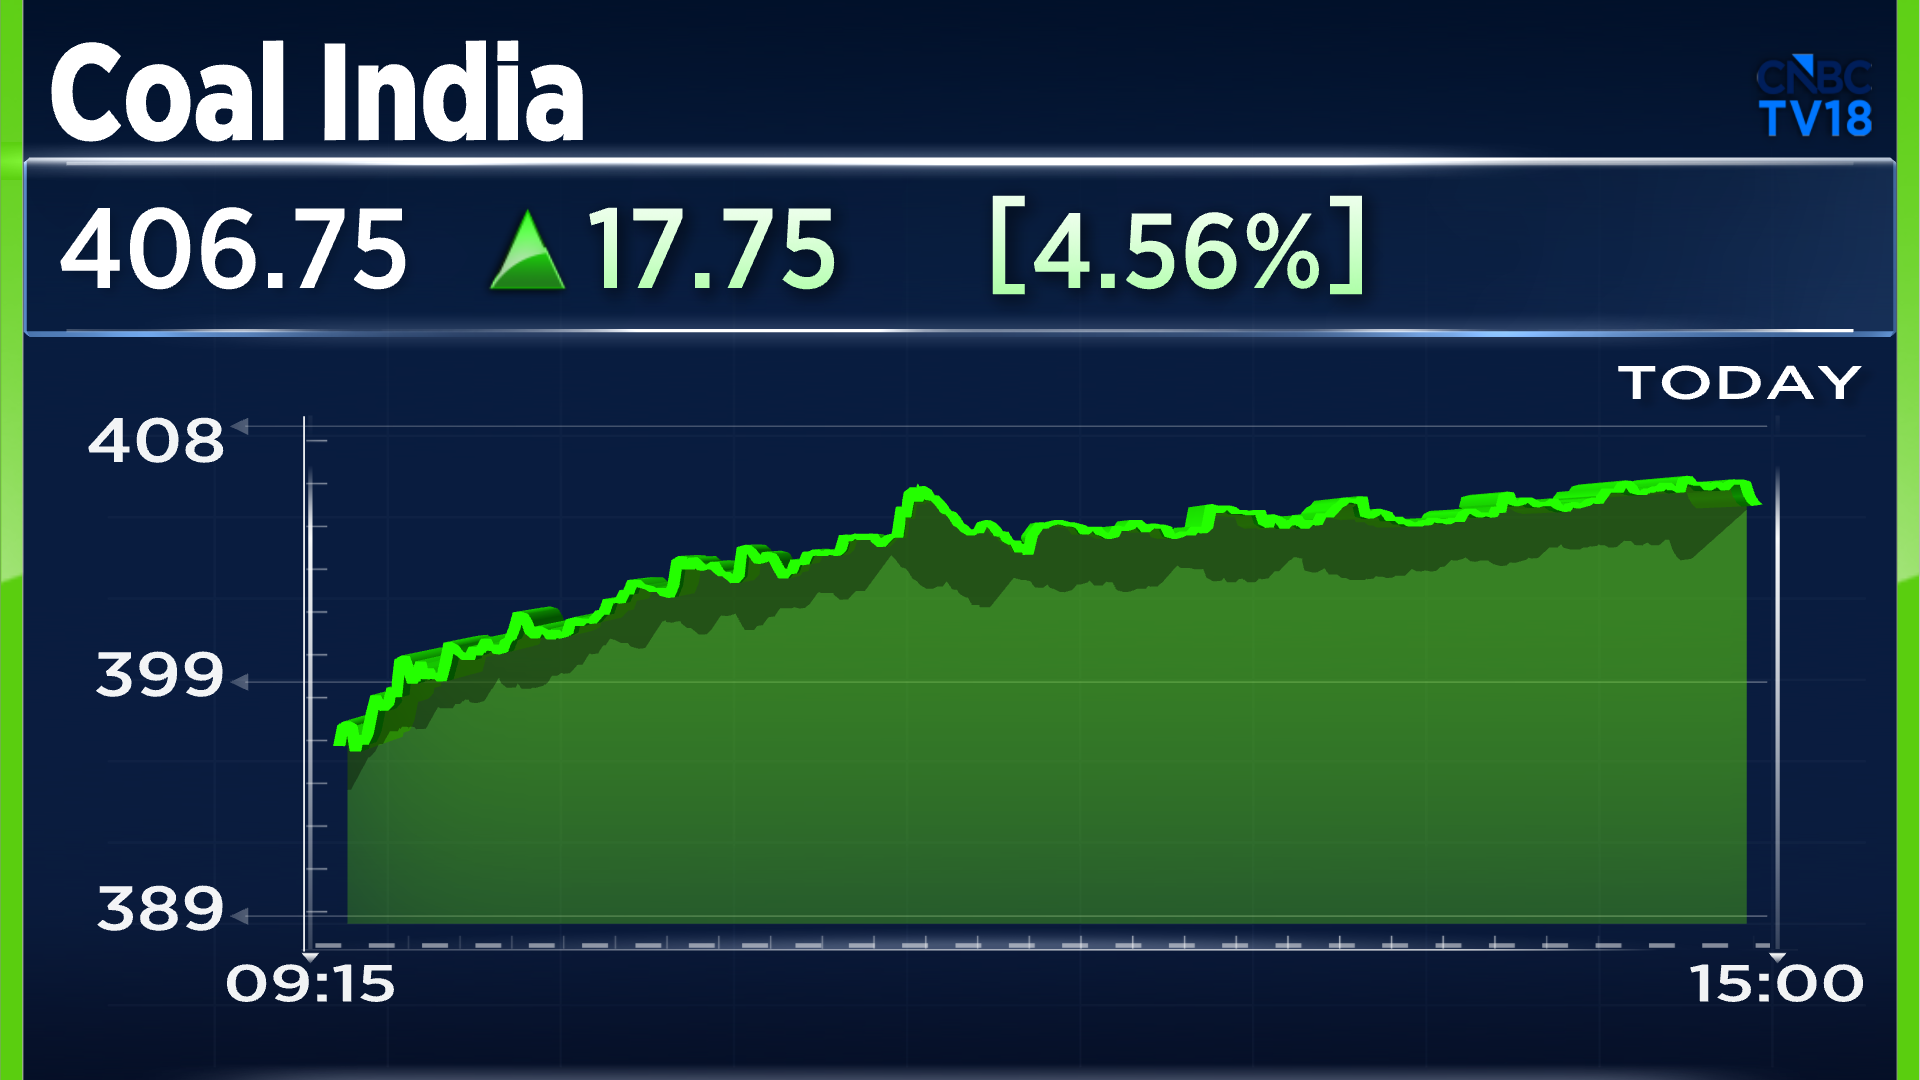
Shares of Coal India gained 5% on Monday, November 2, after the state-run miner reported a strong operational performance in October 2026, with coal production and offtake registering growth of nearly 19% year-on-year (YoY).
Production also touched an October high across financial years, according to the company update.
Coal production increased 19.3% YoY to 67.2 million tonnes (MT) in October, compared with 56.4 MT in the year-ago period. Offtake rose 18.7% to 70.3 MT from 59.2 MT.
The improvement in production and offtake comes alongside firm e-auction premiums. The premium over notified Fuel Supply Agreement (FSA) prices remained above 90% for the second consecutive month, at 90% in October, compared with 94% in September. The premium averaged 54% in the first half of FY27.
E-auction premiums and outlook
Market expectations are that e-auction premiums could remain elevated, supported by firm international coal prices, declining Indonesian exports and low inventory levels at both Coal India and power plants.
Also read: India’s coal production spikes, imports shrink
Sustained premiums could support realisations, although their trajectory will remain an important monitorable alongside production and offtake growth.
Axis Capital on Coal India: ADD, target price ₹445
Axis Capital has maintained an ‘Add’ rating on Coal India with a target price of ₹445. This implies an upside of more than 14% from Friday’s closing price of ₹389. At the current market price of ₹407.45, the implied upside stands at 9.2%.
The global investment firm cited an improving earnings outlook and attractive valuations, with the stock trading at 4.8 times its FY28 estimated enterprise value to EBITDA (EV/EBITDA).
Another factor to watch is the proposed listing of Coal India’s subsidiaries Mahanadi Coalfields (MCL) and South Eastern Coalfields (SECL) in the second half of FY27. Proceeds from the planned listings could also pave the way for a special dividend, according to the investment view shared.
Coal India Q2 results: Profit rises 53%
Coal India reported a 53% YoY increase in net profit to ₹6,516 crore for Q2FY27, beating the CNBC-TV18 poll estimate of ₹6,418 crore. Revenue rose 20.9% to ₹44,179 crore, also ahead of the poll estimate of ₹41,602 crore.
EBITDA increased 28.9% to ₹8,499 crore, but missed the poll estimate of ₹9,220 crore. EBITDA margin improved to 19.2% from 18% a year ago, although it remained below the expected 22.2%.
The company’s board declared a second interim dividend of ₹10.25 per equity share for FY27. November 4, 2026, is the record date, with payment scheduled on or before November 27.
Production remains an important monitorable. Coal India produced 321 million tonnes in H1 FY27, down 2.5% YoY and around 39% of its full-year target of 815 million tonnes. It will need to produce approximately 494 million tonnes in the second half to meet the target. However, September production and offtake showed signs of recovery, rising 9.2% and 12.5%, respectively
Analysts’ view and Coal India stock price reaction
Analyst recommendation data according to Bloomberg shows a largely positive outlook on Coal India, with 18 analysts recommending a ‘Buy’, five assigning a ‘Hold’ rating and two recommending a ‘Sell’.
Shares of Coal India gained as much as 4.9% to an intraday high of ₹408 following the October production update. The gains have taken the stock into positive territory year-to-date, with Coal India shares advancing nearly 2% so far in 2026 and 5% in the trailing 12 months.