
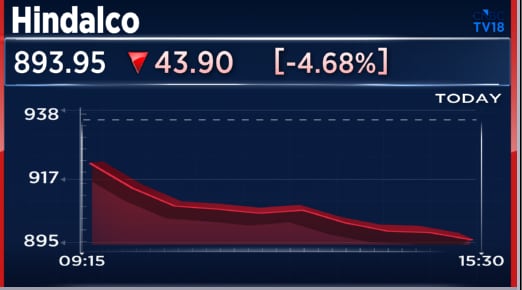
Shares of Hindalco Industries Ltd. opened as much as 4% lower on Friday, November 6, after its subsidiary Novelis reported its September quarter (Q2FY27) results, with higher reported adjusted EBITDA but continued pressure on underlying operating performance, alongside an increase in net debt.
Novelis reported a 20.4% year-on-year increase in adjusted EBITDA to $508 million in Q2FY27, compared with $422 million in the corresponding quarter last year. Adjusted EBITDA per tonne also improved to $553 from $448 a year ago.
However, shipment volumes declined to 919,000 tonnes from 941,000 tonnes in Q2FY26, indicating softer volumes during the quarter.
The reported EBITDA includes $39 million in insurance recoveries received during Q2FY27. Excluding these recoveries, EBITDA stood at $469 million, unchanged from the previous quarter (Q1FY27). Adjusted EBITDA per tonne, excluding insurance recoveries, was $510, compared with $512 in the preceding quarter.
Novelis had received $47 million in insurance recoveries in Q1FY27.
Higher costs and operational challenges weigh on performance
Novelis’ operating performance was affected by higher tariffs and a labour strike at its South Korean facility in September. The strike resulted in an estimated negative impact of $20 million due to production losses during the month.
The impact of US import tariffs also increased to $78 million in Q2FY27, compared with $70 million in the previous quarter. This was primarily due to higher imports required to meet customer demand in North America.
The fire-affected Oswego facility has returned to normal operations, although it is temporarily experiencing lower customer demand.
The company also reported a significant working capital outflow of $356 million during the quarter, while capital expenditure stood at $768 million.
Management expects to release around $300 million of working capital from inventory in the second half of FY27. It is also targeting a reduction in its net debt-to-EBITDA ratio to 4x by the end of FY27.
Novelis raises cost-saving target
On the cost-efficiency front, Novelis has achieved more than $240 million in annualised run-rate savings through Q2FY27. The company expects this figure to reach $300 million by the end of FY27.
It has also raised its cumulative savings target to $350-400 million by the end of FY28, compared with its earlier estimate of more than $300 million.
What brokerages are saying
CLSA has an ‘Outperform’ rating on Hindalco Industries, with a price target of ₹1,240. The brokerage said that Novelis’ adjusted EBITDA per tonne of $553 came in below estimates, despite a $39 million benefit from Oswego-related insurance recoveries, equivalent to around $43 per tonne.
Production at the fire-affected Oswego facility has normalised, although the ramp-up has led to higher tariff costs of around $85 per tonne. The labour strike at Novelis’ South Korean facility had an estimated impact of approximately $20 per tonne.
The strike has since been resolved. However, Novelis expects a similar impact in Q3FY27, while tariff-related headwinds are expected to taper to near zero by Q4FY27 as domestic production in the US increases.
The Bay Minette facility remains on track to begin commercial shipments in Q1FY28, with full utilisation expected within two years.
Novelis expects to generate positive free cash flow and reduce debt from Q4FY27, supported by lower capital expenditure and further insurance recoveries.
JPMorgan has an ‘Overweight’ rating on Hindalco, with a price target of ₹1,165. The brokerage said that the commissioning of the Bay Minette facility remains on track, with the first coil produced in September 2026.
Insurance recoveries related to the Oswego fire are progressing, with recoveries of $519 million in the first half. Novelis expects total recoveries to reach $900 million by the end of FY27 and $1.3 billion by the following year.
Novelis continues to face tariff-related headwinds, with the impact amounting to $78 million in Q2. This was primarily driven by higher shipments from its Kingston facility in Canada to meet customer requirements in the US, as supply from Oswego gradually normalises.
These tariff-related pressures are expected to ease by the end of FY27 as Novelis shifts more production to the US.
Novelis also announced that its CFO will step down in mid-January 2027. The company has not yet announced a successor.
Shares of Hindalco Industries settled 0.22% higher at ₹937.85 on Thursday, November 5. The stock has gained around 5% so far in 2026.
Hindalco shares fall 4% after analysts cite Novelis margin pressures but see recovery in FY27