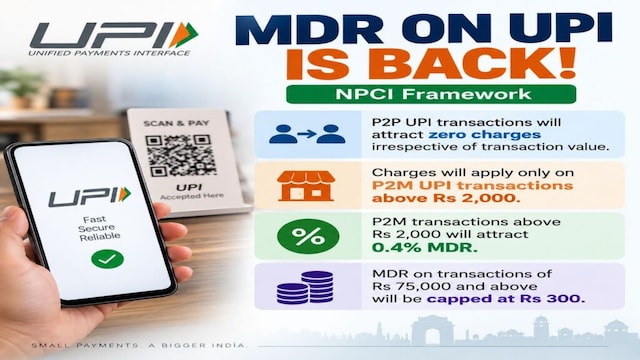
Choksey said companies that have spent heavily on payment infrastructure without generating adequate returns are now positioned to benefit as MDR income starts flowing into their revenue.
According to Choksey, payment companies such as CCAvenue, Paytm and Pine Labs are likely to capture a significant share of the additional revenue created by the new framework. He estimates CCAvenue alone could see an incremental revenue of ₹80 crore to ₹110 crore, with most of it flowing through to operating profit because infrastructure costs are already in place.
“That money which they have been up till now spending will get realised… it should get reflected into the profits of the company going forward.”
While banks are also expected to benefit from the estimated ₹16,000-20,000 crore revenue opportunity across the ecosystem, Choksey believes acquiring banks will mainly use the additional income to recover infrastructure costs.
Asked to name one stock to watch, Choksey pointed to AvenuesAI, saying its potential earnings benefit appears more visible based on current calculations. He added that Paytm should also benefit from the new regime.
Largecap weakness needs institutional buying
Choksey attributed the weakness in largecap stocks to a lack of buying interest and aggressive short positions in the derivatives market.
He said many fundamentally strong companies have come under pressure because institutional buying has remained absent.
According to Choksey, a reversal in the trend will require participation from large funds.
“Unless we see some major buying coming into the largecaps, this situation is not going to reverse.”
AI will support, not replace, Indian IT services
Choksey also dismissed the view that a slowdown in global artificial intelligence (AI) spending would automatically revive traditional IT services.
He compared the current stage of artificial intelligence to the early years of the internet, arguing that AI will create new business opportunities rather than replace existing technology services.
He said Indian IT companies are increasingly adapting their business models to AI-led products and services, supported by healthy balance sheets and execution capabilities. While he expects near-term upside to remain limited, he believes downside risks are also contained because of strong fundamentals.
Solar Industries acquisition remains a long-term positive
Solar Industries shares declined after announcing a large acquisition. Choksey said the market’s initial reaction was understandable given the company’s valuation and the increase in debt.
However, he described the acquisition as strategically important because it expands the company’s footprint in Africa and strengthens its mining-related operations.
He also noted that the acquisition will add revenue and earnings before interest, taxes, depreciation, and amortisation (EBITDA) over time, although investors may have to wait for valuations to stabilise before considering fresh investments.
Choksey said the deal could temporarily increase leverage but believes it positions Solar Industries for long-term growth by creating a larger business with a broader international presence.
For the full interview, watch the accompanying video
Catch all the latest updates from the stock market here