
Kotak Securities upgraded the defence electronics company to “Add” from its earlier rating of “Reduce,” citing an improved risk-reward profile following the stock having corrected over 8% during the last three months.
The brokerage though, has cut its price target for BEL to ₹410 from ₹420 earlier. The revised price target implies an upside potential of 6.5% from Monday’s closing price for BEL.
Defence pipeline supports long-term outlook
Kotak Securities remains constructive on BEL, supported by a strong pipeline of large defence programmes, including Quick Reaction Surface-to-Air Missile (QRSAM), Advanced Medium Combat Aircraft (AMCA) and naval programmes such as Project-75 India (P75I) and Next Generation Corvette (NGC).
The brokerage also sees missiles and exports emerging as key medium-term growth drivers for the company.
However, it flagged execution and margin normalisation as key risks. Despite these concerns, healthy order prospects and long-term visibility on defence spending support its constructive view on the stock.
As a result of these challenges and risks, Kotak Securities has lowered its financial year 2028-2029 Earnings Per Share (EPS) estimates by 4% to reflect more moderate execution assumptions.
Analysts remain bullish on BEL
Bharat Electronics is a near-consensus “buy” among analysts who cover the stock. 37 out of the 38 analysts covering it have a “buy” rating on the stock, while one solitary analyst has a “sell” recommendation.
The consensus estimates of price targets implies an upside potential of 27% from current levels.
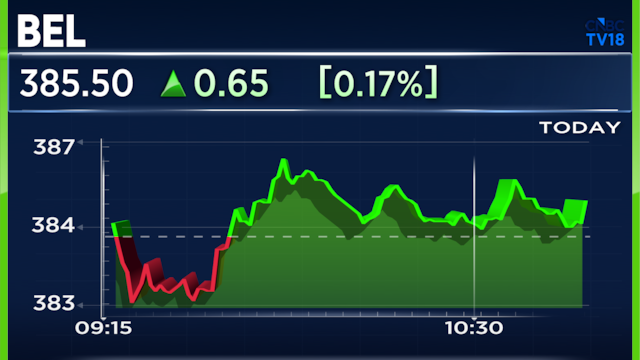
Shares of Bharat Electronics are trading little changed on Tuesday at ₹384.8. The stock is down 5% in the last one month and as a result, the stock has turned negative on a year-to-date basis.
Also Read: Reliance Industries weightage increased in Jefferies model portfolio; Check the two new inclusions