
Brokerages Citi and Goldman Sachs reiterated their positive stance on the stock after the update, with the latter even raising its price target to ₹540 post the update.
Q2 business update
Kotak Mahindra Bank’s net advances-end of period (EOP) increased by 24.7% from last year to ₹5.77 lakh crore.
Its current account savings account (CASA) deposits-EOP was up 11.3% in the second quarter at ₹2.39 lakh crore.
Meanwhile, its deposits were up 23.2% from last year to ₹6.51 lakh crore.
Citi
The brokerage has a “buy” rating and a target price of ₹465 per share. This indicates an upside of 11.8% from its previous close.
It said the company delivered a marked step-up in balance sheet momentum in the second quarter, with FCNR(B) deposit mobilization lending additional thrust to an already robust sequential accretion.
Citi said its gross advances of 24.7% from last year and 12.7% from the previous quarter were well ahead of their estimates of 20.9% and 9.2%, respectively.
It said stripping out leveraged impact of $1.68 billion in FCNR(B)-linked exposure, the lender’s core advances growth stood at 21.6% from the previous year and 9.5% on a sequential basis. This still comfortably outpaced the brokerage’s estimate, a beat Citi attributed to the continued strength in corporate banking, SME, LAP and MFI segments.
Kotak Mahindra Bank’s average net advances expanded 22.1% on an annual basis and 10.5% on a quarterly basis. Its EOP deposits growth came in at 23.2% from last year and 13.7% from the previous quarter, outpacing Citi’s estimate of 20% and 10.8%, respectively.
Excluding the $5.78 billion FCNR(B) accretion, its core deposit growth was at 13.5% from last year and 4.1% in the previous quarter.
Average deposits increased 18.8% from the previous year and 8.5% in the previous quarter.
Goldman Sachs
The brokerage has a “buy” rating and has raised its target price to ₹540 per share. This indicates an upside of 29.8% from its previous close.
It said the lender’s second quarter performance was strong on mobilization of FCNR(B) flows.
Its organic loan growth accelerated sharply to 19% from the previous quarter’s 15% from the previous year.
Goldman Sachs said the bank’s deposit growth was strong, helped by strong FCNR(B) flows. It has a better clarity on leadership, strong liquidity position at the bottom of the rate cycle, potential acceleration in loan growth led by unsecured loans amid cheap valuations.
The bank’s profitability and earnings inflect, the brokerage expects the stock to compound as well as re-rate from current levels.
It has raised its earnings to factor stronger-than-expected deposit flows as well as bigger and faster rate hike cycle.
According to Goldman Sachs, Kotak’s valuation of 15 times its financial year 2028 price-to-earnings ratio, based on an Earnings Per Share (EPS) growth of 19% is “very attractive.”
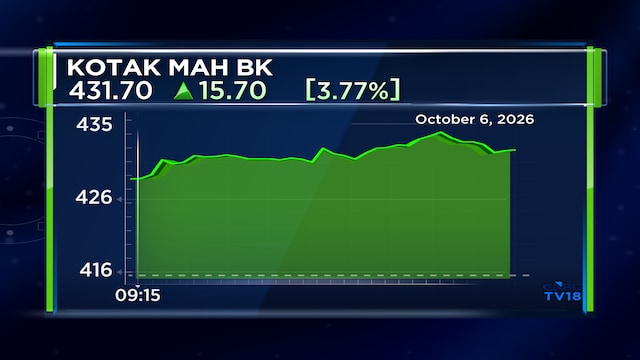
Shares of Kotak Mahindra Bank are trading 3.7% higher on Tuesday at ₹431.25. The stock is still down 3% so far on a year-to-date basis.
Also Read: Honasa Consumer shares jump 7% after projecting another robust quarterly performance in Q2