
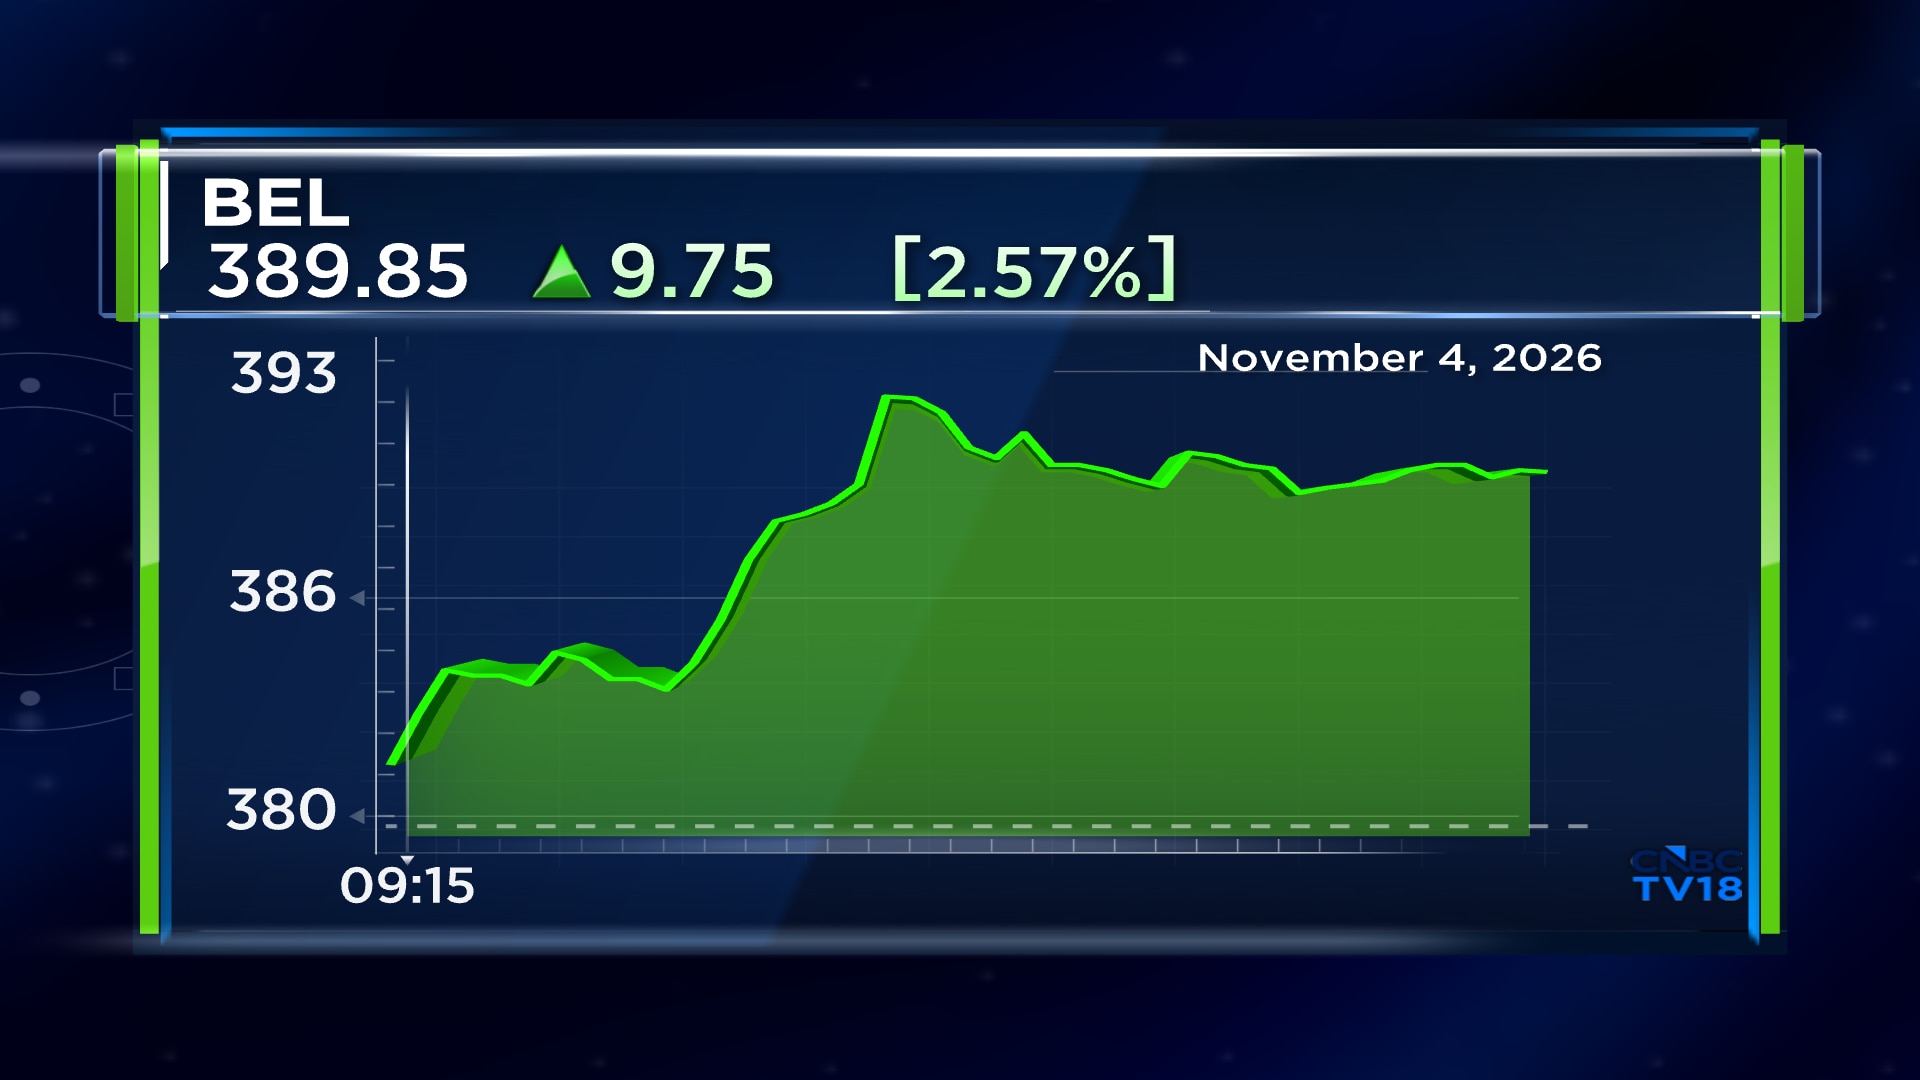
Shares of Bharat Electronics Ltd. (BEL) gained over 3% on Wednesday, November 4, as brokerage firm Motilal Oswal retained its estimates and revised its target price higher after the company’s second quarter results and guidance.
Motilal Oswal reiterated its “buy” rating on BEL and revised its target price to ₹540 per share from its previous ₹530. This indicates an upside of 42% from its previous closing price.
Motilal Oswal said BEL’s second quarter revenue, EBITDA and profit after tax (PAT) came in above its estimates. It said its EBITDA margin also remained strong, led by better project mix.
The company’s base order inflows declined 31% as ordering is yet to ramp up meaningfully from the defence ministry, Motilal Oswal said. A large order such as QRSAM, worth ₹30,000 crore is delayed and BEL is hoping to receive it at the next CCS meeting. BEL is also hopeful of a large order worth ₹20,000 crore from next-generation corvettes.
The brokerage said that there have been certain delays by the ministry of defence in finalizing projects, but it expects inflows to ramp up in the coming quarters.
Motilal Oswal expects BEL’s revenue to grow at a Compounded Annual Growth Rate (CAGR) of 15%, EBITDA to grow at a 14% CAGR and PAT to grow at another 15% CAGR over financial year 2026-2029.
The revised price target on BEL values the stock on a roll-forward 45 times its December 2028 estimates.
BEL has reiterated its FY27 guidance and is expecting revenue growth of 15%, an earnings before interest, depreciation and amortization (EBITDA) margin of 28% and order inflows of more than ₹55,000 crore, including the QRSAM programme.
The company is also planning to invest more than ₹2,200 crore in research and development and ₹1,200 crore in capex during the yar, while it maintains a business mix of 90% defence and 10% non-defence,
Motilal Oswal said the non-working days in the first half of the financial year 2027 were lower than those of March 2026, with inventory and receivable days declining, thereby bolstering operating cash flows. Motilal Oswal expects operating cash flow (OCF), free cash flow (FCF) to remain strong, led by control over working capital.
The stock is currently trading at 40x, 34x and 30x its price-to-earnings on FY27, FY28, FY29 earnings per share (EPS).
On another note, global investment banking firm Nomura also has a “buy” rating and a target price of ₹530 per share on the BEL stock.
Key risks For BEL
Motilal Oswal said the following factors can adversely impact its estimates on BEL’s revenue, margins and cash flows:
- A slowdown in order inflows from the defence and non-defence segments.
- Intensified competition.
- Further delays in the finalization of large tenders.
- A sharp rise in commodity prices.
- Delays in payments from the Ministry of Defence.
BEL shares are a Buy Or Sell?
Of the 38 analysts who have coverage on the BEL stock, 37 have a “buy” recommendation and one has a “sell” rating.
Shares of BEL are trading 2.7% higher on Wednesday at ₹390.3. The stock is flat on a year-to-date basis, trading with a 2% decline.
Also Read: CleanMax share price: Macquarie sees upside to FY27 estimates, sets ₹1,700 target after Q2