
Shares of Ambuja Cements Ltd. were trading lower on Friday, November 20, even as Jefferies maintained its “Buy” rating on the stock with a price target of ₹475, implying an upside potential of around 20% from the current trading level.
Following its interaction at the Adani Group conference, Jefferies highlighted the company’s improving volume outlook, focus on profitability and cost-reduction initiatives as key factors shaping its growth prospects.
Volume growth expected to improve in second half
Ambuja Cements expects volume growth to improve in the second half of FY27 compared with the first half, according to management commentary at the conference.
The company reiterated its focus on value over volume, indicating that it would continue to let go of unprofitable sales rather than chase volumes at the expense of margins.
Also read: Explained – Why Kotak expects this Tata Group stock to fall 24% despite the recent rally
Pricing has also shown signs of improvement. Cement prices increased by around ₹10 or more per bag in October, following a largely stable pricing environment during the monsoon quarter.
The contribution of premium cement to the company’s overall sales mix has risen to 37%, reflecting its focus on higher-realisation products.
Cost reduction and expansion plans
Ambuja Cements is targeting a cost reduction of ₹250 per tonne by the end of this financial year. It also aims to bring its cost per tonne down to around ₹4,000 by financial year 2028, from the current level of ₹4,410 per tonne.
The company is looking to achieve these efficiencies through greater use of renewable energy, improvements in logistics and operational measures.
Alongside cost optimisation, Ambuja has initiated its next phase of expansion, with plans to add around 30 million tonnes of capacity. The expansion will be focused on markets across the North, West and East, where the company sees better profitability opportunities.
Management is also prioritising higher-realisation trade volumes as part of its broader focus on improving profitability rather than pursuing volume growth alone.
Ambuja-ACC merger progressing
The consolidation of the group’s cement businesses is also progressing. The merger of Ambuja Cements and ACC is expected to be completed during the current financial year, according to the management update.
The consolidation is part of the group’s efforts to streamline its cement operations as it pursues its next phase of capacity expansion and cost efficiencies.
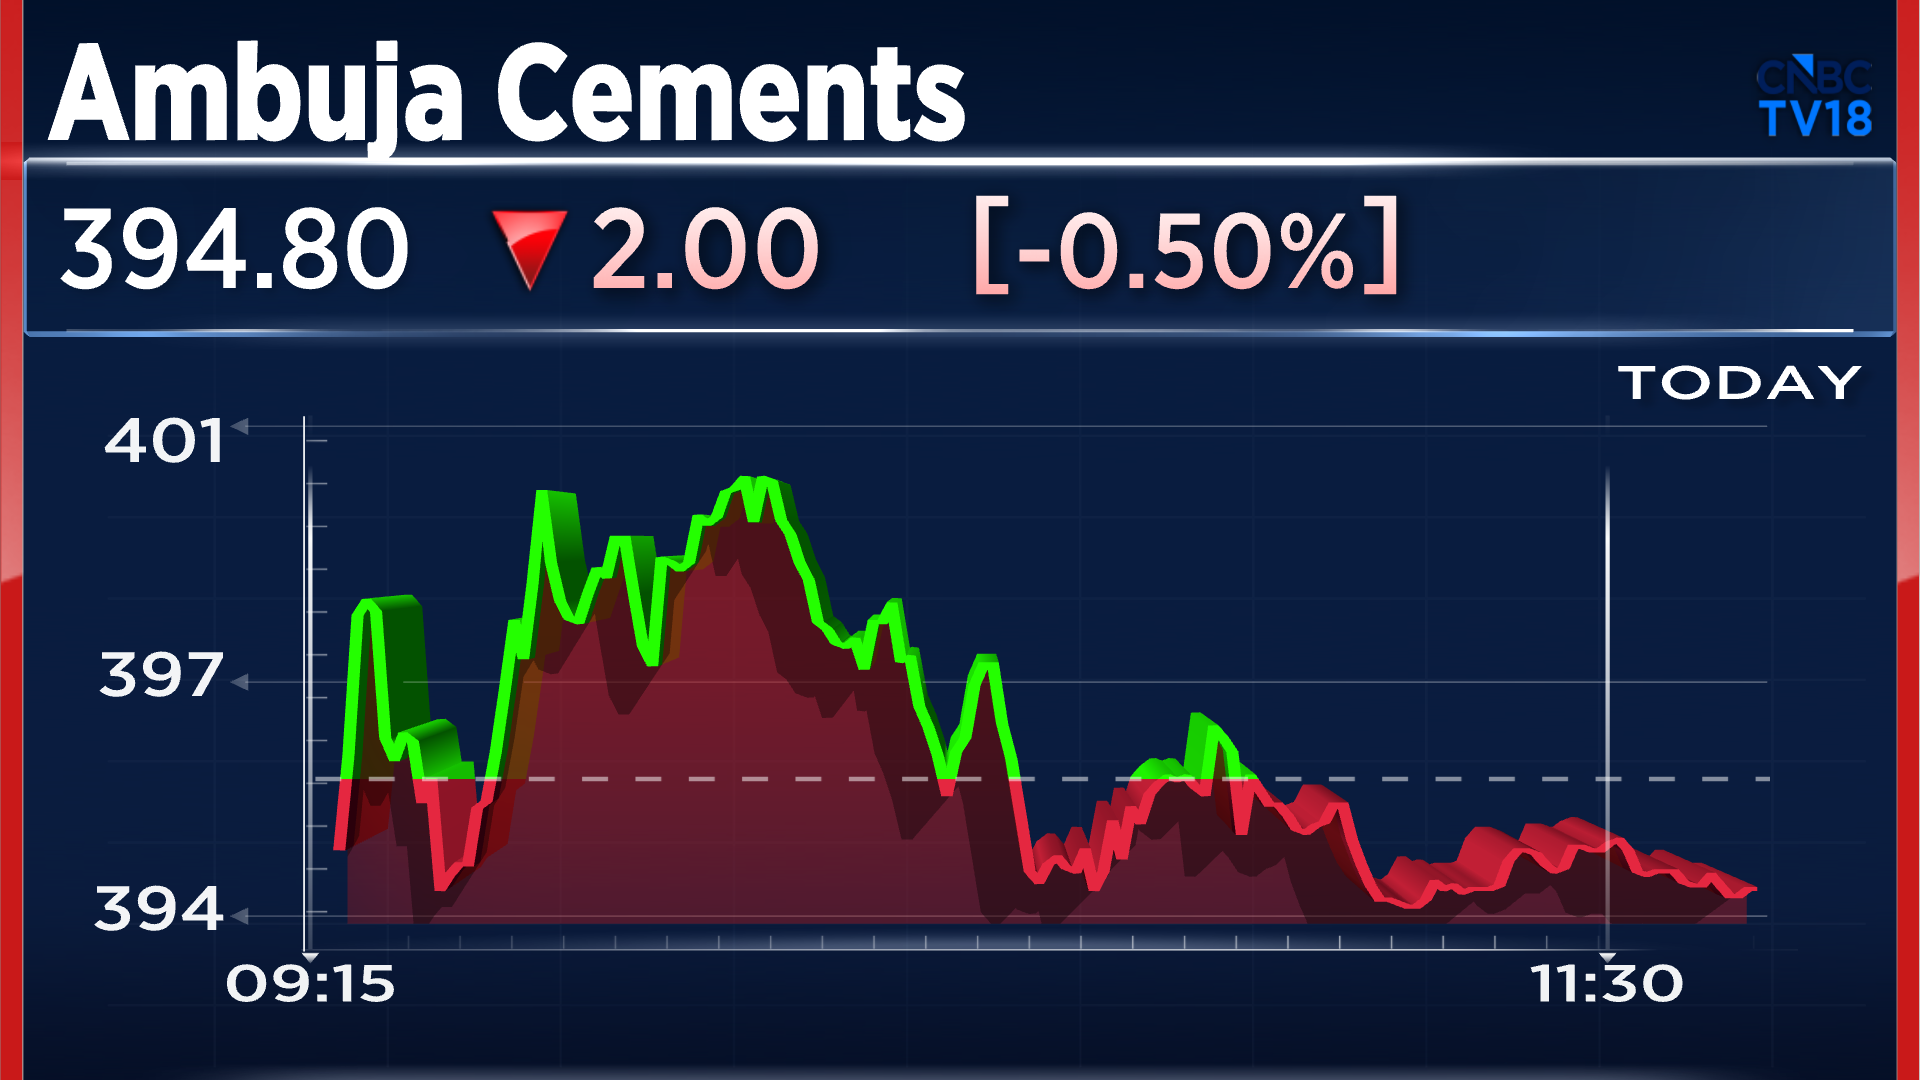
Shares of Ambuja Cements are looking to recover from the lows of the day, currently trading little changed at ₹396.3. The stock is down 30% so far this year.
Ambuja Cements Share Price: Jefferies sees 20% upside on volume recovery and cost cuts