
Platform company Eternal’s aggressive store expansion could support ‘higher for longer’ growth in its quick commerce business, though replicating metro-level profitability in smaller towns remains a key challenge for Blinkit, according to Jignanshu Gor, Director and Senior Research Analyst at Bernstein.
Following Eternal‘s solid quarterly numbers, the brokerage noted a distinct shift in the quick-commerce narrative. Gor said, “The increase in guidance for number of stores, and they will accelerate by almost 50% the number of stores that they add every quarter versus what they have done in the past, and do it for longer, which means the growth will be higher for longer.”
This could support growth, although it may delay profitability.
However, Gor cautioned against assuming that the margins achieved in major cities would automatically translate across a much larger store network. He said consumer behaviour, purchase frequency and product mix in smaller towns could differ significantly from those in metros, creating uncertainty around the business model.
Read Here | Eternal share price can rise 35% after Q2 results, Motilal Oswal says; Check other price targets
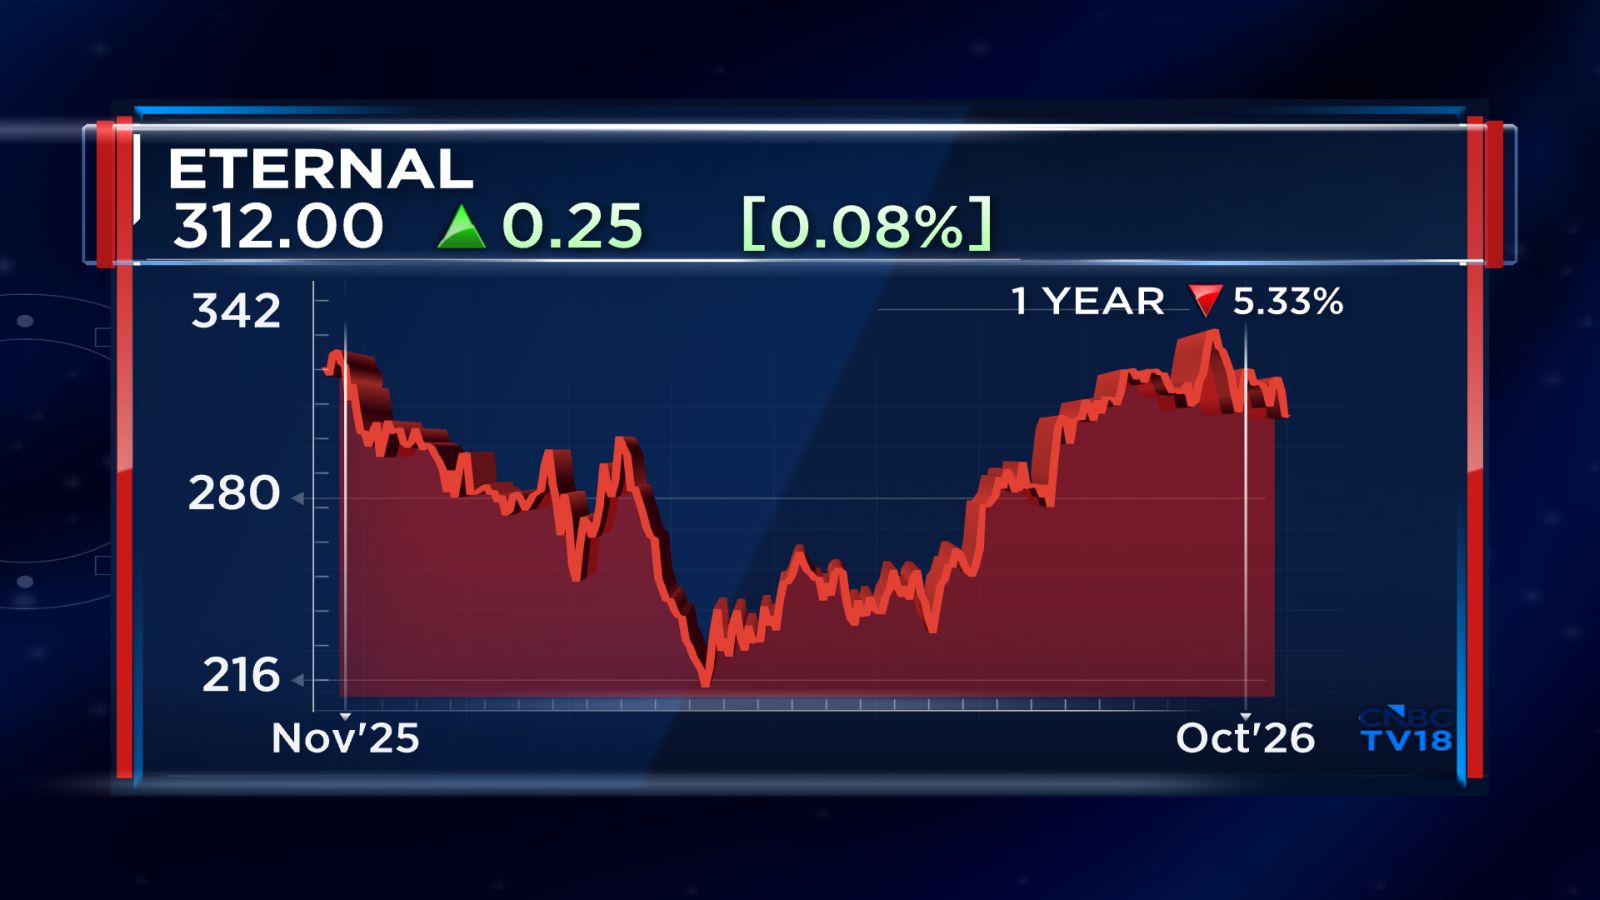
The stock was trading at ₹314.95 at 9:22 am on the NSE and has declined more than 4% over the past year.
“We do not doubt the growth trajectory. All we are saying is we are slightly more cautious in putting the same margin profile that we have seen in metro cities into a much larger store base,” Gor said.
Bernstein maintains a $1 billion EBITDA estimate for the Blinkit business in 2030, but remains cautious about projecting the same margin profile seen in the top 10 cities—which are broadly EBITDA profitable—across a 500-city footprint.
“There is a novelty effect associated with getting something faster, but a lower frequency purchase does not make a consumer as sticky as a higher frequency purchase in metros,” Gor explained, highlighting the uncertainties of addressing a different consumer base and product mix in new geographies.
Meanwhile, Eternal is actively driving the narrative around artificial intelligence, stepping ahead of global platform peers. However, it remains too early to assign any sum-of-the-parts valuation to these AI initiatives until the exact plans and right-to-win become clear.
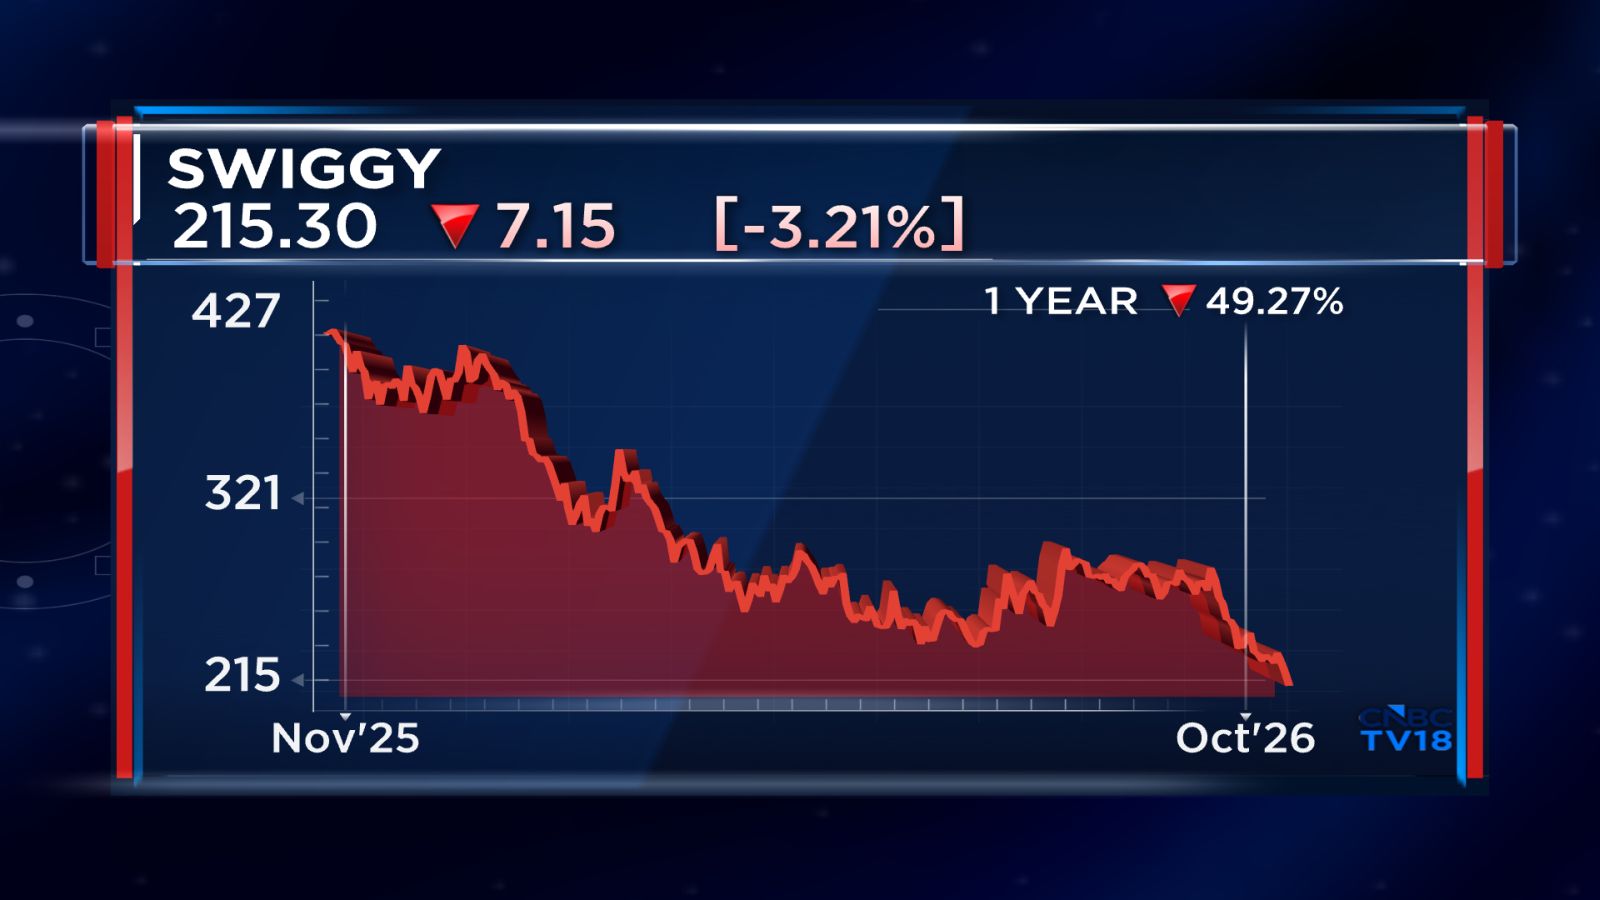
The stock was trading at ₹213.95 at 9:22 am on the NSE and has declined more than 49% over the past year.
Ahead of Swiggy‘s earnings, the rival platform is anticipated to show better performance against its own benchmarks, though it is unlikely to match Blinkit’s numbers or communication.
With the stock having taken a beating, there is a case for evaluating Swiggy on its own fundamentals rather than drawing direct comparisons to Eternal, as the two are increasingly playing different games. Despite this, the market leader remains the preferred pick in the space.
For the entire discussion, watch the accompanying video

Bernstein flags margin risks as Eternal accelerates Blinkit store expansion
Live stock market updates—follow our blog
NOTE TO READERS
Disclaimer: The views and investment tips expressed by investment experts on CNBCTV18.com are their own and not that of the website or its management. CNBCTV18.com advises users to check with certified experts before taking any investment decisions.