
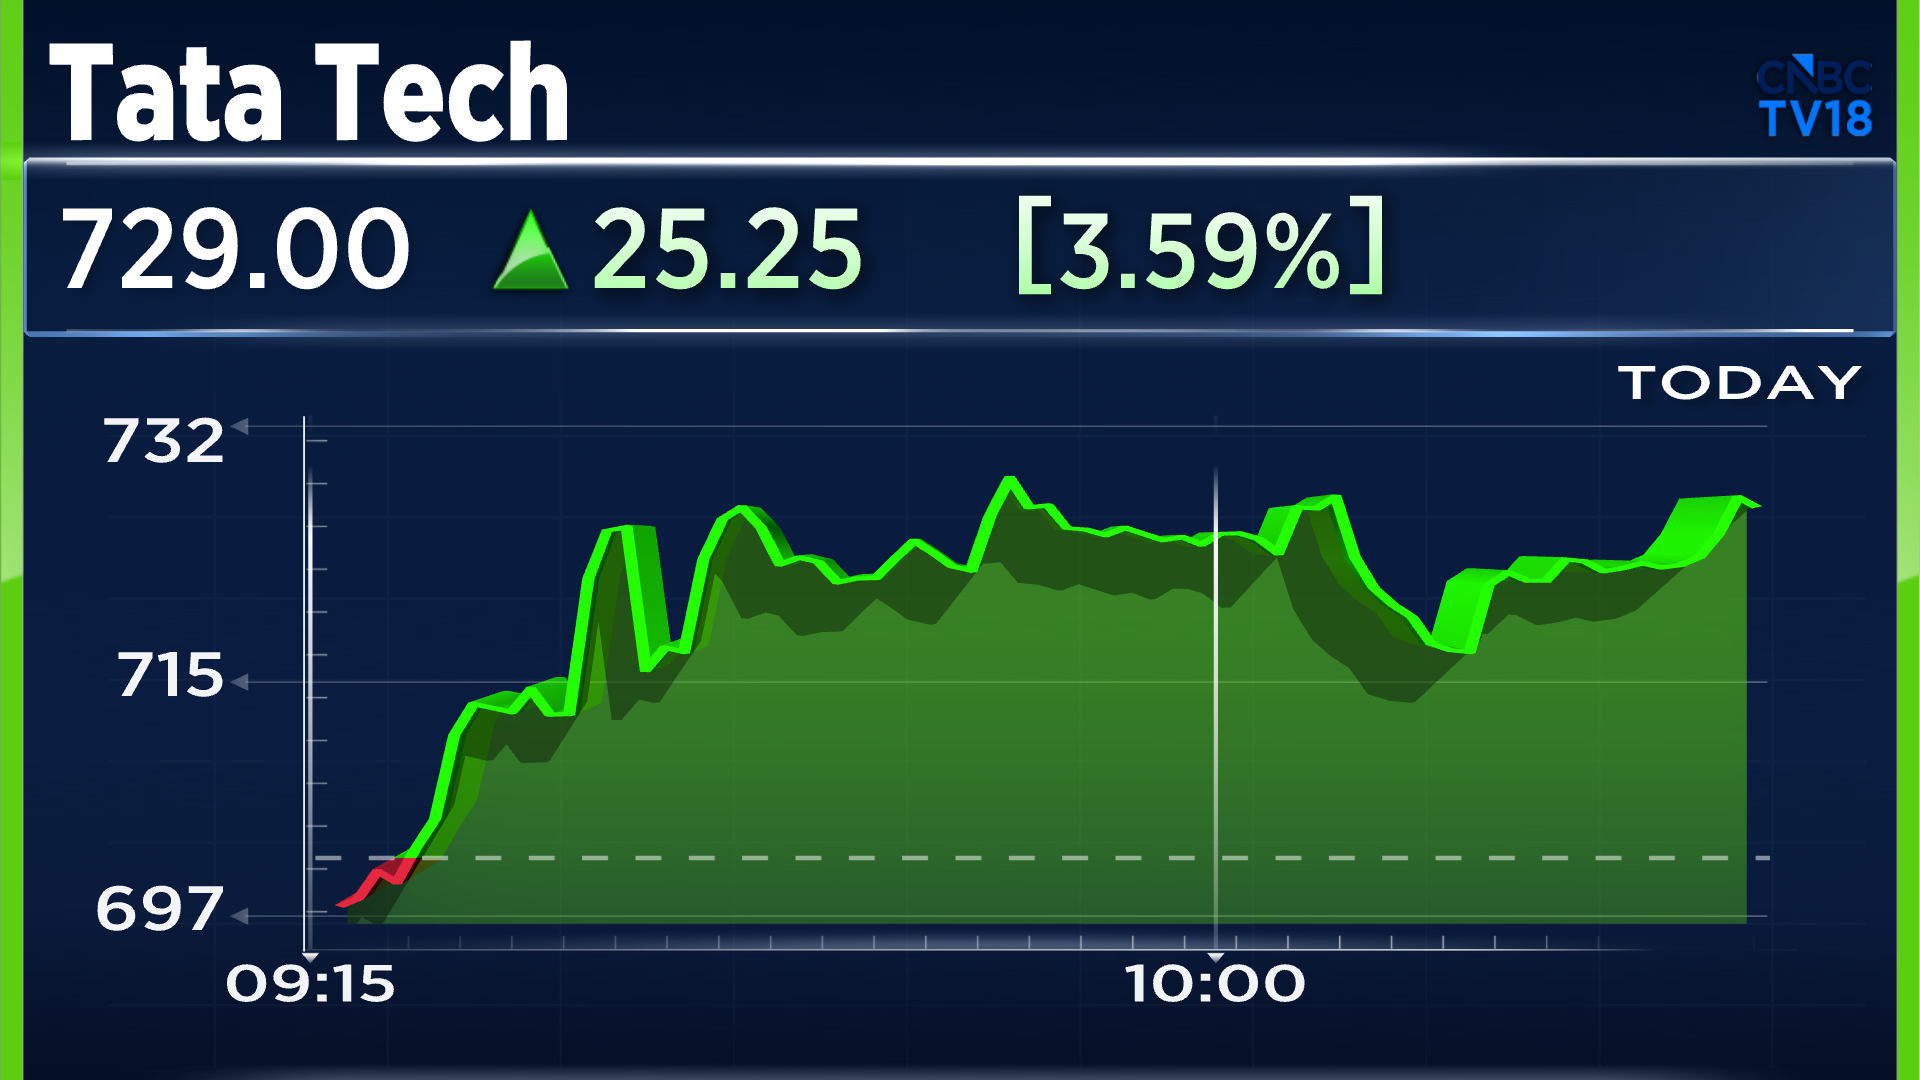
Shares of Tata Technologies Ltd. rose as much as 4% on Friday, November 20, extending their gains for a second consecutive session, even as Kotak Institutional Equities maintained a ‘Sell’ rating on the stock with a target price of ₹535.
The target implies a downside of around 24% from Thursday’s close at ₹703.75.
Kotak’s cautious view comes after Tata Technologies outlined its medium-term growth and profitability ambitions at its analyst day. The company is targeting a sharp increase in revenue and margins over FY2026-30, but Kotak believes meeting these elevated goals will require tighter execution and a broader improvement in demand.
Tata Technologies sets ambitious growth targets
In its investor call on Thursday, Tata Technologies said it aims to double its revenue to $1.1 billion-$1.3 billion and expand its earnings before interest, tax, depreciation and amortisation (EBITDA) margin by at least 450 basis points to above 20% over FY2026-30.
Also read: Tata Technologies Q2: Profit declines 5%, misses estimates; revenue grows 28%
The company expects revenue to grow at a compound annual growth rate (CAGR) of 15%-20% between FY27 and FY30. Its software and aerospace businesses are expected to grow at a faster pace, with revenue from both verticals projected to increase at a Compound Annual Growth Rate (CAGR) of 25%-30%.
Tata Technologies has also set specific targets for its individual businesses. It aims to double the size of its software business over the next three years and generate $100 million in revenue from aerospace by FY28. Tata Technologies is also targeting a return on equity (ROE) of around 20% over the medium term, while maintaining a dividend payout ratio of more than 50%.
The company told CNBC-TV18 that its strategy was to move from strength to scale, with a focus on outcome-based business targets. It said its order book and pipeline supported confidence in its growth outlook.
Management expects margins to improve by around 100 basis points each year, with the FY27 exit rate targeted at 17%. It also expects economies of scale to support profitability, while artificial intelligence (AI) could help optimise the organisation’s overhead structure.
M&A, services and automotive demand in focus
Tata Technologies said acquisitions would focus on filling capability gaps and improving customer access. Companies with annual revenue of around $30 million-$50 million, and potentially up to $70 million, are considered the preferred size for acquisitions, although it remains open to larger opportunities.
The company expects the services component of its business to grow sequentially in the December quarter, while technology solutions could remain soft. It expects an improvement in the second half of the year and said demand trends and outsourcing decisions by automotive original equipment manufacturers (OEMs) would be important factors.
Management also pointed to a $138 million award secured last month from a luxury automotive OEM and said BMW had committed to its joint venture with the company.
Tata Technologies expects growth in its software business to remain strong, supported by demand for its engineering and technology solutions.
Analysts remain cautious
Of the 18 analysts covering the stock, four have a ‘Buy’ rating, five have a ‘Hold’ rating, and nine have a ‘Sell’ rating. The average 12-month target price is ₹718, indicating a potential downside of over 1%.
Shares of Tata Technologies jumped up to 4% to touch an intraday high of ₹732. The stock has gained more than 10% over the last two sessions and is up around 12% so far in November, breaking a two-month losing streak.
The shares are trading above their 50-day and 200-day moving averages, but remain below the 100-day average. Its Relative Strength Index (RSI) stands at 62.7, indicating positive momentum but remaining below the threshold typically associated with overbought conditions.
Tata Tech has gained nearly 13% so far in 2026 and about 7% over the trailing 12-month period.
Explained – Why Kotak expects this Tata Group stock to fall 24% despite the recent rally