The revised target implies an upside of around 15% from Thursday’s closing price of ₹3,344.40. Along with the target-price increase, Investec raised its FY27 and FY28 profit estimates by 10% and 13%, respectively, while Earnings Before Interest, Tax, Depreciation and Amortisation (EBITDA) estimates were increased by 7% and 9% for the same time period.
The brokerage now expects Supreme Industries’ revenue to grow at a 12% Compounded Annual Growth Rate (CAGR) between FY26 and FY29, with EBITDA growing at a 15% CAGR over the same period. Normalised net income is expected to rise from ₹954 crore in FY26 to ₹1,446 crore by FY29.
Investec raises earnings estimates
Investec raised Supreme Industries’ FY27 revenue estimate by 3% to ₹12,576 crore, while its FY28 estimates have been increased by 6% to ₹13,773 crore.For FY29, Investec expects Supreme Industries’ revenue to reach ₹15,563 crore, from ₹11,218 crore in FY26. EBITDA is projected to rise from ₹1,553 crore to ₹2,398 crore, while normalised net income is expected to increase from ₹954 crore to ₹1,446 crore.
The brokerage forecasts an average free cash flow yield of around 1.9% between FY26 and FY29.
JJM funding revival could support volumes
Investec said the earnings outlook is improving after two years of subdued growth, with a potential revival in Jal Jeevan Mission (JJM) execution providing a key volume driver.
The brokerage expects the audit cycle around JJM funding to be largely behind the company, with reports from the Centre and states now under legislative scrutiny. The central government released no JJM funds in FY26, but Investec expects releases to resume, with initial fund flows to some states already visible.
A revival in funding and on-ground execution could make Supreme Industries a major beneficiary, given its exposure to the pipes segment.
Investec is factoring in a relatively conservative 12% volume CAGR for FY26-FY29, compared with the historical 14% and 13% volume CAGR over the past three and five years, respectively.
The brokerage expects average EBITDA per kg of ₹23 over FY27-FY29, compared with historical three-year and five-year averages of ₹22 and ₹24, respectively.
Also read: Bernstein bets on this drugmaker for 28% upside citing a key value driver for the future
PVC prices offer additional support
Domestic PVC prices have risen from ₹82 per kg on June 25 to ₹98 per kg on September 7 and ₹103 per kg currently, Investec noted.Based on parity calculations and an assumed 5% local premium, the brokerage sees scope for a further ₹10 per kg increase in PVC prices.
Quarter-to-date average PVC prices are around 10% higher than the average during the first quarter of FY27, which Investec expects could result in inventory gains in Q2 FY27 and potentially beyond. Higher realisations could also support revenue growth and fixed-cost absorption.
The brokerage said ongoing countervailing duty investigations involving Chinese PVC remain a variable to monitor.
Supreme Industries valuation, risks
Investec has shifted its valuation basis to September 2028 and now values Supreme Industries at 36 times price-to-earnings, compared with 40 times on its earlier March 2028 basis. This supports the revised target price of ₹3,860.
Key risks include increasing competition in plastic piping, volatility in crude and resin prices, and regulatory measures affecting PVC.
Supreme Industries has no debt on its balance sheet, according to Investec’s estimates. Net cash is projected to be ₹6,515 crore in FY27 and ₹13,957 crore in FY28.
Analysts view and stock movement
According to Bloomberg data, 22 of 30 analysts covering Supreme Industries have a “Buy” rating, while six have a “Hold” rating and two have a “Sell” rating. Investec’s ₹3,860 target is below the consensus estimate, and it stands among the more conservative targets.
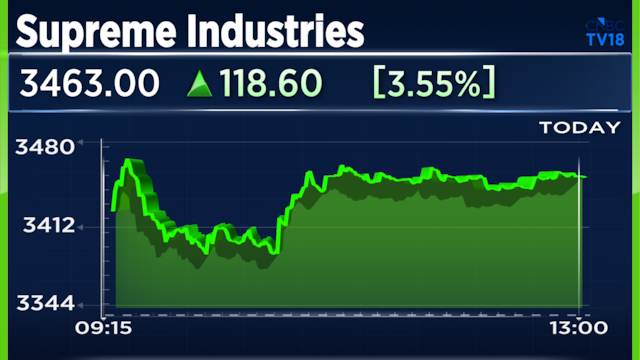
Shares of the company were trading near the day’s highs at ₹3,461.30 on Friday, up 3.5% from Thursday’s close. The stock has fallen about 23% in the last 12 months.