
The revised target implies an upside of more than 17% from ITC’s Friday closing price of ₹255.90.
The upgrade comes as Citi believes the earnings downgrade cycle is largely over for ITC and said the stock’s current valuation offers an improving risk-reward profile. The brokerage noted that the stock’s 34% year-to-date correction has already priced in risks around a potential cigarette tax hike.
Cigarette tax hike largely priced in
Citi estimates that around 75% of any tax increase has been passed on through price hikes. It expects calibrated pricing actions to support cigarette profitability even as the business faces near-term volume pressure.
The brokerage expects cigarette volumes to remain under pressure in the near term as higher prices affect consumption. However, new product launches could help ITC retain consumers and limit downtrading.
It also flagged competition from illicit cigarettes and other branded products as a risk to the cigarette business.
Despite the near-term volume pressure, the brokerage expects cigarette profitability to improve sequentially through FY27.
Citi also noted that consensus earnings per share (EPS) estimates for FY27 and FY28 have been cut by 23% and 21%, respectively, year-to-date.
ITC: Analysts’ views and stock performance
According to Bloomberg analyst-rating data, ITC has a consensus Buy rating, with 21 of 38 analysts recommending a Buy, 15 on Hold and two on Sell. The 12-month consensus target price stands at ₹326.03, implying an upside of about 21% from the current price.
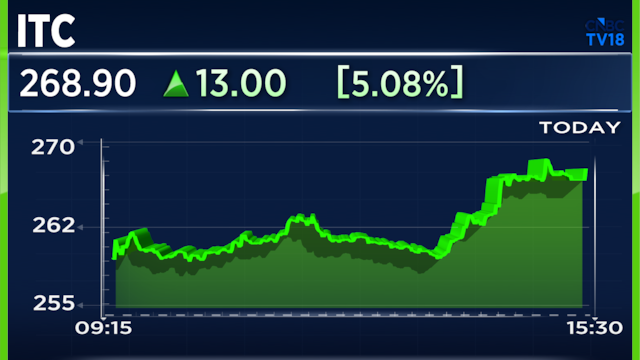
ITC shares ended near the day’s highs at ₹267.80 on Monday, up nearly 5%. The stock has declined more than 26% so far in 2026 and over 33% in the last one year.
Also read: Nykaa shares jump over 5% as Q2 NSV growth tops 30%; Goldman Sachs raises price target