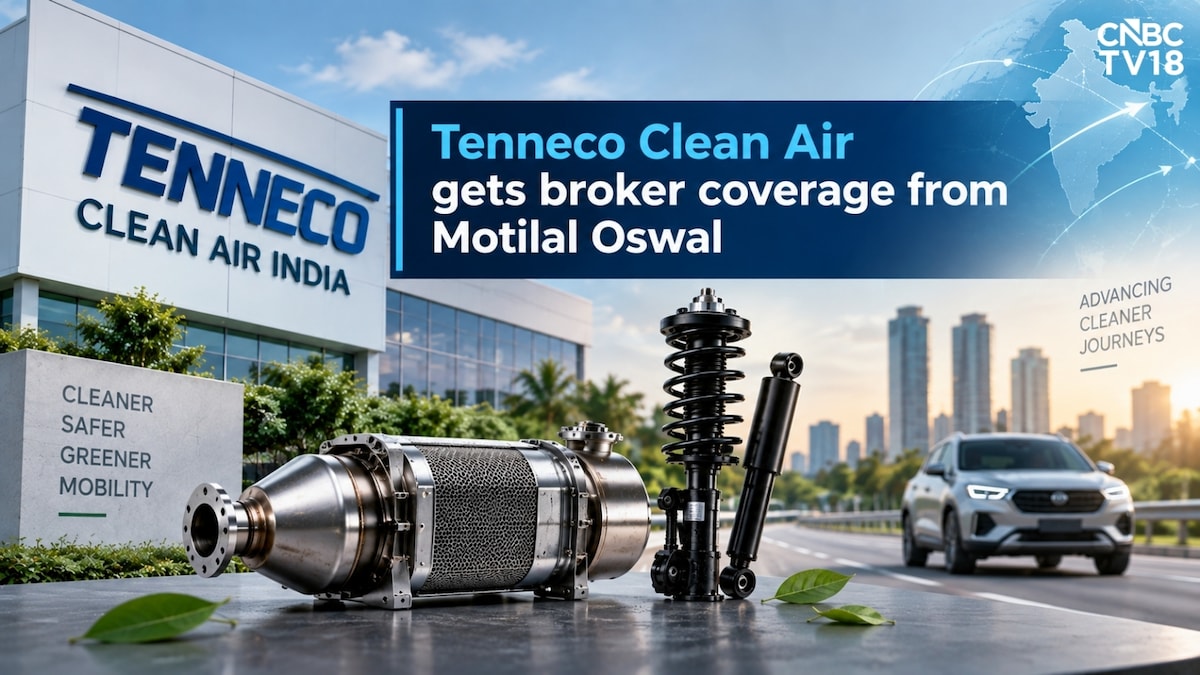
The brokerage’s base case target implies an upside of 33% from the stock’s Friday closing price of ₹506.35.
MOFSL expects Tenneco Clean Air to enter its next phase of growth on the back of its leadership across clean-air and suspension products, tighter emission norms, vehicle premiumisation, new customer programmes and rising exports.
The brokerage estimates a 19% earnings Compound Annual Growth Rate (CAGR) between FY26 and FY29, while clean-air and powertrain revenue is expected to grow at around 17% CAGR over the same period.
The company’s order book stood at ₹12,400 crore as of March 31, 2026, providing more than 100% coverage of its FY28 revenue target, according to MOFSL.
Strong market position
Tenneco Clean Air has around 58% market share in clean-air products supplied to commercial vehicle OEMs, 68% in off-highway applications excluding tractors, and 20% in passenger vehicles. It also has around 55% share in passenger-vehicle shock absorbers and struts.
MOFSL said the company’s integration with the global Tenneco network gives it access to technology, intellectual property, global OEM relationships, research and development capabilities and manufacturing expertise. Its involvement in customer product-development cycles also creates high switching costs, the brokerage said.
Key growth drivers for Tenneco Clean Air
The brokerage sees BS-VII, CAFE III and TREM-V as important drivers of higher content per vehicle.
For commercial vehicles, BS-VII and related emission requirements are expected to increase clean-air content, while lower penetration in light commercial vehicles leaves room for market-share gains.
Tractors represent a significant opportunity, with the 30-50 HP segment accounting for more than 90% of the market. MOFSL expects TREM-V to potentially increase clean-air content to ₹5,000 – ₹7,000 per vehicle as after-treatment penetration rises.
In passenger vehicles, BS-VII and CAFE III could increase clean-air content by around 1.3 times, driven partly by greater adoption of gasoline direct injection and gasoline particulate filters. A Japanese OEM GPF programme is expected to add to Tenneco’s hot-end business from 2028.
The company has also secured a new clean-air engine platform with a major Indian CV OEM, a programme with a leading European commercial vehicle OEM and a CNG platform cold-end assembly programme covering two models from a global OEM.
Also read: Here’s why Afcons Infra share price surged as much as 20% on Tuesday
Suspension business to grow 20%
MOFSL expects the suspension business to clock around 20% CAGR during FY26-FY29, supported by premiumisation, exports, higher share of business and increasing adoption of advanced suspension systems.Tenneco has around 55% share of India’s passenger-vehicle suspension market. Its DaVinci DCx, commercialised with Mahindra in February 2026, offers around 85-90% of the comfort of a semi-active system at a significantly lower cost. MOFSL believes the technology can address the ₹10-35 lakh passenger-vehicle segment, which accounts for around 70% of the market.
Tenneco Clean Air exports to rise
Tenneco Clean Air is also being positioned as a manufacturing and export hub within the global Tenneco network, with products supplied across North America, Europe, Asia-Pacific and Africa.
The company currently exports to around 18-22 countries, while MOFSL expects exports to increase to 15% of value-added revenue by FY29 from 7% currently. Exports account for around 14% of the current order book and generally carry higher margins than domestic business, according to the brokerage.
Motilal Oswal on Tenneco’s financial estimates
MOFSL expects Tenneco’s revenue to rise from ₹5,404 crore in FY26 to ₹8,985 crore by FY29. Earnings Before Interest, Tax, Depreciation and Amortisation (EBITDA) is projected to increase from ₹925.5 crore to ₹1,560.8 crore over the same period, with the EBITDA margin expanding from 17.1% to 17.4%.
Adjusted profit after tax is estimated to rise from ₹630.4 crore in FY26 to ₹1,026 crore in FY29, while EPS is expected to increase from ₹15.6 to ₹25.4.
The brokerage expects the company’s strong balance sheet to support this growth. Tenneco Clean Air has a net cash position, negative working capital and core RoCE above 90%, while cash-flow conversion is expected to remain healthy, with CFO/EBITDA above 70% and FCF/PAT above 80%.
Tenneco Clean Air valuation
At MOFSL’s reference price of ₹506, the stock was trading at 26.1 times FY28E earnings and 19.9 times FY29E earnings. The brokerage has valued the stock at 30 times September 2028 earnings to arrive at its ₹673 target.
Motilal Oswal’s bull case assumes 22.7% revenue CAGR through FY29, full implementation of BS-VII, slower EV adoption and faster suspension growth. This scenario gives Tenneco Clean Air a price target of ₹886, implying an upside potential of around 75% from the current price.
Its bear case assumes 15% revenue CAGR because of delays in BS-VII, slower DaVinci adoption and faster EV penetration. The resulting target is ₹521, implying around 3% upside from the reference price.
Key risks to watch
MOFSL flags faster-than-expected EV adoption, termination of the technology licence or private-equity exit overhang, intensifying competition, commodity-price fluctuations and loss of key customers as the main risks.
The brokerage also notes that Tenneco’s powertrain business remains exposed to the transition away from ICE vehicles, while competition from established players such as Bosch, Denso and NGK remains a longer-term risk.
Analyst consensus and stock movement
Motilal Oswal has now become the seventh firm to cover Tenneco Clean Air, of which six have a “buy” rating and one has a “sell” recommendation.
Shares of Tenneco Clean Air India are off the highs of the day but are still trading 2.4% higher on Tuesday at ₹519. The stock is trading just above its IPO price of ₹397 per share.