
Shares of Samvardhana Motherson International Ltd. were trading higher on Wednesday, November 11, extending their gains for a third consecutive session.
The stock gained on Wednesday after global investment banking firm Citi raised its price target on the stock, but continued to have a bearish stance on it.
Citi maintained its “sell” rating on Samvardhana Motherson but raised its price target on the stock to ₹140 from ₹115 earlier. The revised price target implies a downside potential of 15% from current levels for the auto component manufacturer.
The target price revision follows the company’s September quarter results, which came in ahead of estimates, supported by strong revenue growth across key segments and contributions from recent acquisitions.
Samvardhana Motherson reported its highest-ever quarterly revenue of ₹38,280 crore in Q2FY27, up 8.6% year-on-year from ₹35,244 crore. Consolidated net profit increased 13.9% to ₹1,175 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) rose 8.4% to ₹3,357 crore. EBITDA margin remained steady at 8.7%.
The company’s booked business reached a record $106 billion, providing visibility on future orders.
In its November 5 research note, Citi said Samvardhana Motherson’s Q2FY27 performance was driven by strong growth across key segments, aided by the integration of Yutaka Giken and Nexans Autoelectric.
The global investment firm has increased its revenue and earnings estimates to factor in higher growth from acquisitions. It has also raised its valuation multiple to 22 times from 21 times, citing a stronger growth outlook supported by new acquisitions. The revised multiple is in line with the stock’s five-year average, Citi said.
However, the firm retained its “Sell” recommendation, citing potential headwinds from weak global passenger vehicle demand, uncertainty around further acquisitions and rising debt.
Global automotive demand remains a concern
Citi said domestic automotive demand remains healthy, with India’s light vehicle production growing 15% year-on-year and commercial vehicle production rising 19%.
Global conditions, however, remain challenging. Light vehicle production declined 2% globally, with output in China falling 5.5%, North America declining 3.8% and Europe contracting 0.6%.
The investment firm flagged weakness in China, geopolitical disruptions and commodity price volatility as key uncertainties for the company.
Following the Q2 results, Samvardhana Motherson Chairman Vivek Chaand Sehgal said the company was focused on identifying and realising synergies from its recent acquisitions. He also highlighted the company’s balance sheet strength, with its leverage ratio at 0.8 times.
Motherson spent ₹3,585 crore on capital expenditure in the first half of FY27 and has set a full-year capex target of ₹6,000 crore, with a variation of 10% on either side. During the September quarter, it operationalised one new plant and announced five expansions. The company also announced the acquisition of Rotary Connectors (India).
Analysts’ view and stock reaction
22 out of the 26 stocks who have coverage on Samvardhana Motherson have a “buy” rating on the stock, while one has a “hold” and the other three have a “sell” rating on the stock. The consensus estimate of price targets implies an upside potential of 13% from current levels.
Shares of Samvardhana Motherson fell more than 5.6% on November 5, following Citi’s research note. However, the company reported its September quarter results after market hours on the same day, posting a better-than-expected performance.
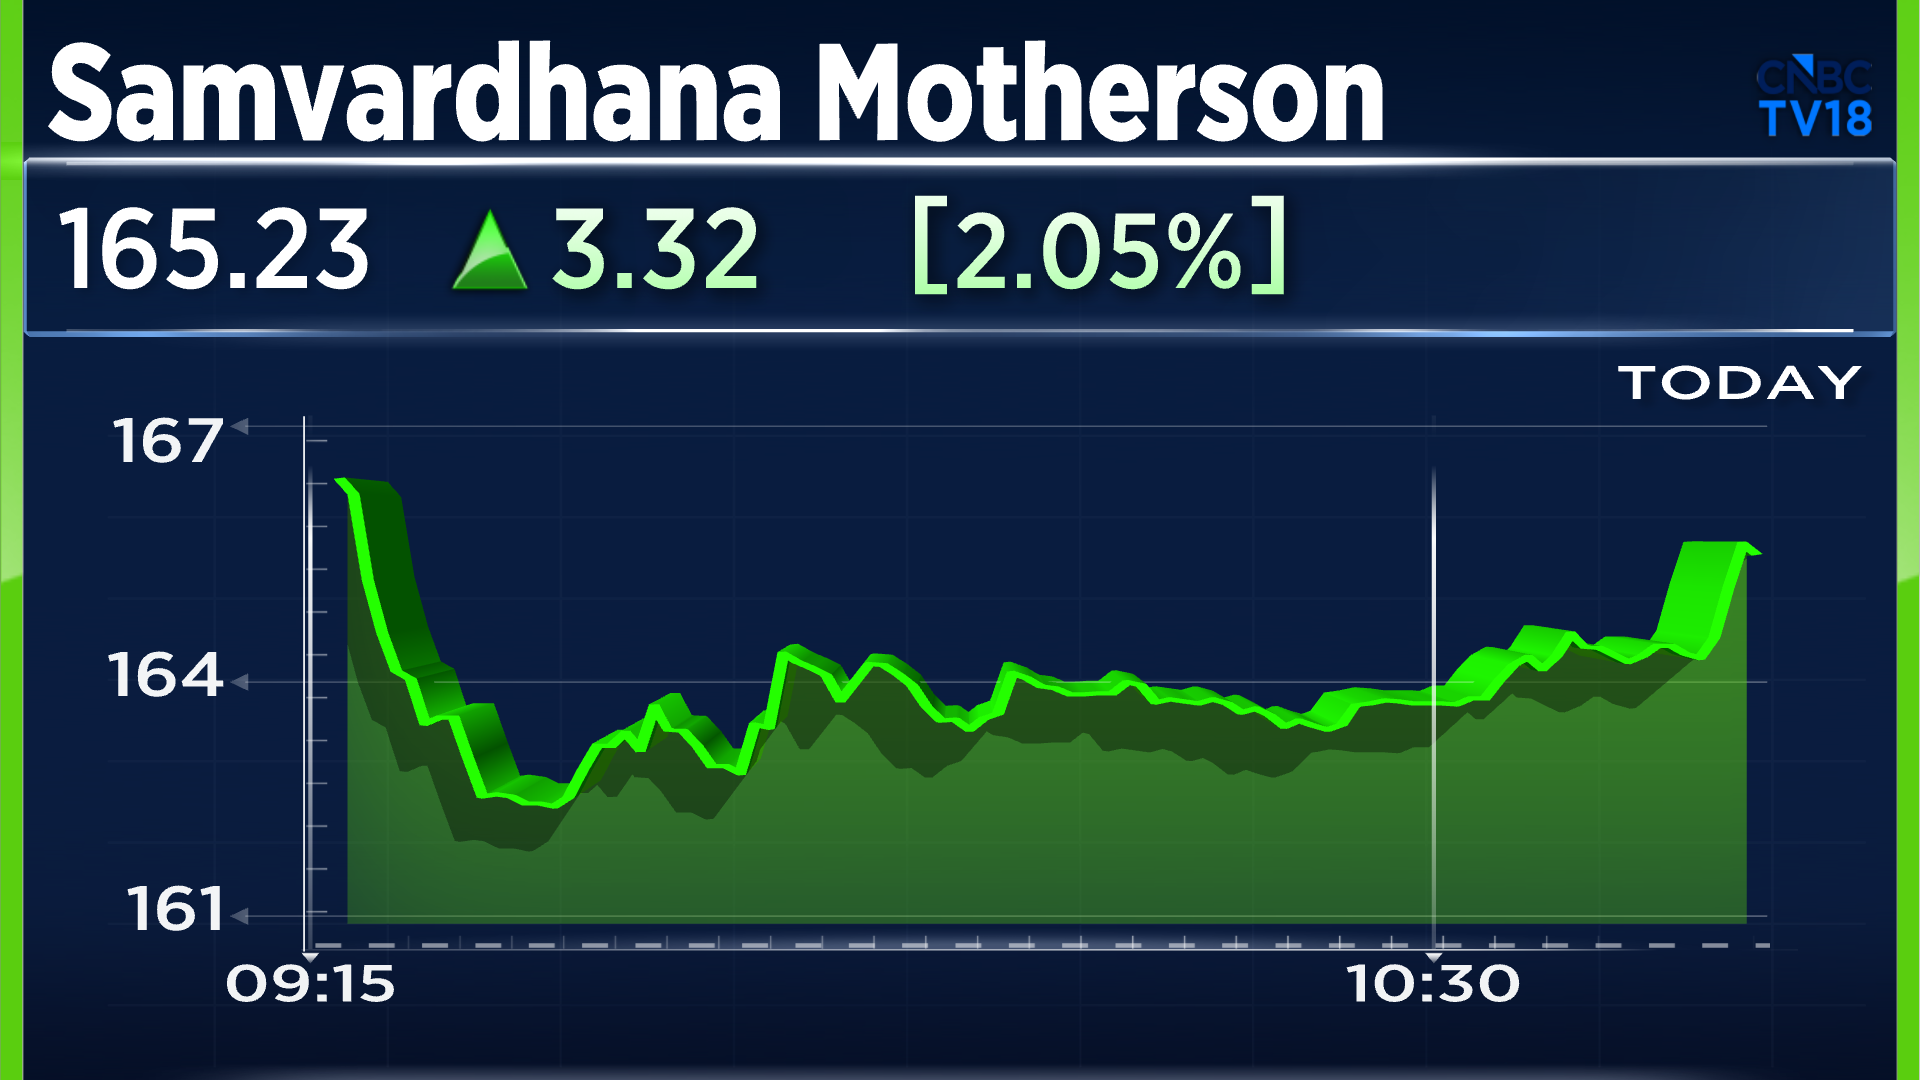
Shares of Samvardhana Motherson are trading 2.8% higher on Wednesday at ₹166.5. The stock is up 35% so far this year.
Samvardhana Motherson is a ‘sell’ candidate according to Citi on these key risks; Check price target