
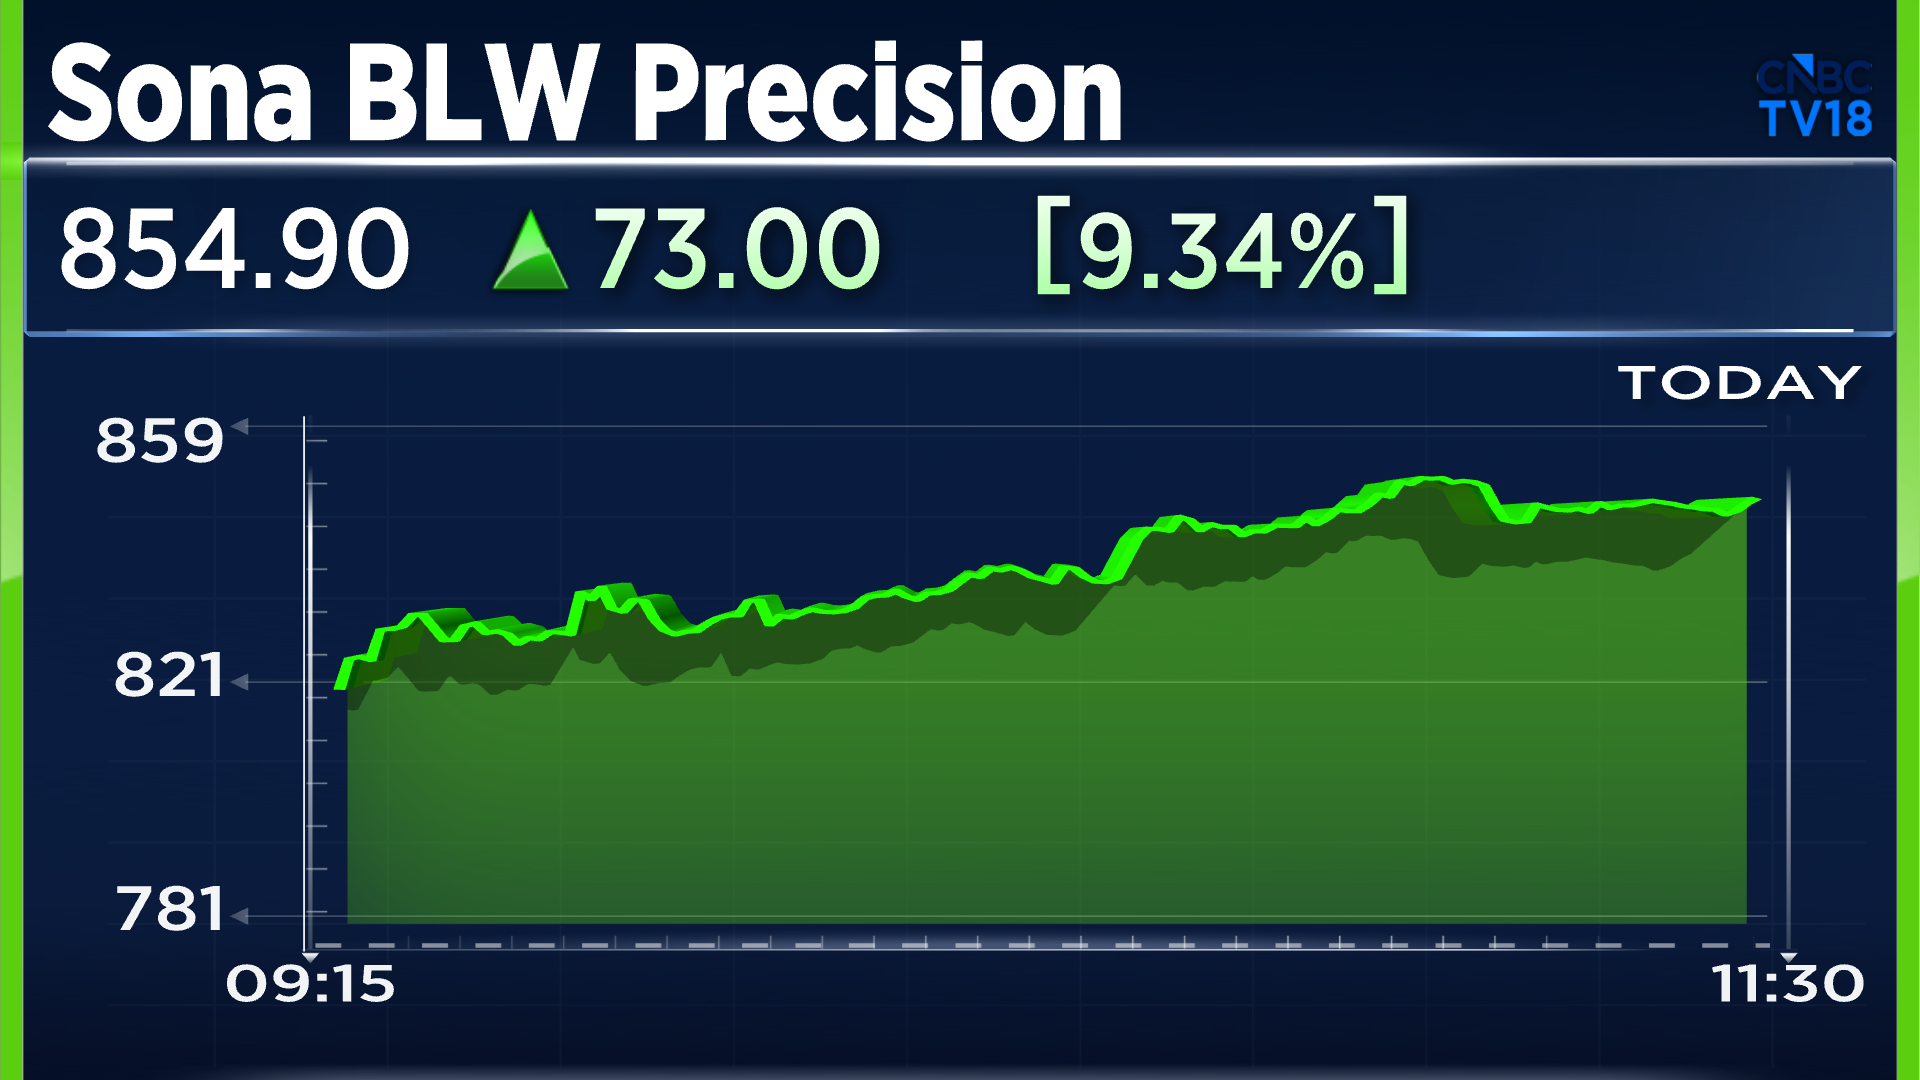
Shares of Sona BLW Precision Forgings Ltd. surged nearly 10% intraday on Tuesday, October 27, after a strong September-quarter earnings performance, with revenue growing 35% year on year and battery electric vehicle (BEV) revenue jumping 129% from the same quarter last year.
This is the biggest single-day jump for the stock since October 2024, when the stock had jumped 13% on October 24.
However, global investment firms do not see significant upside on the stock, with their outlooks signifying a division in their views on the company’s prospects.
Citi’s ₹960 target implies a 23% upside from Monday’s close of ₹781.90, while JPMorgan’s ₹600 target points to a downside of over 23%. Kotak Institutional Equities has also retained a “Sell” rating, citing expensive valuations despite the company’s growth opportunities.
Sona BLW Q2 results
For the September quarter, Sona BLW reported a 29.9% year-on-year increase in net profit to ₹223.4 crore from ₹172 crore in the year-ago quarter. Revenue rose 35.2% to ₹1,546.4 crore from ₹1,144 crore. Margins narrowed on higher cost of material but the fall was in-line with expectations.
The company’s battery electric vehicle (BEV) revenue more than doubled, rising 129% year-on-year to ₹606.1 crore. BEV revenue accounted for 51% of automotive product revenue during the quarter.
Sona BLW received orders worth ₹3,600 crore during the quarter. Its net order book stood at ₹25,100 crore at the end of the first half of FY27, the second-highest level on record. Electric vehicle and Robotics and Physical AI programs accounted for 65% of the net order book.
What global investment firms say
Citi: Buy | Target price raised to ₹960
Citi maintained a Buy rating and raised its target price to ₹960 from the earlier level of ₹830. Based on Monday’s close of ₹781.90, the target implies an upside of about 23%.
The global investment firm said Sona BLW delivered a strong second-quarter earnings beat, driven by robust revenue growth. It highlighted positive trends in suspension motors, traction motors and differential assemblies, along with a favourable demand outlook supported by global electric vehicle and domestic electric two-wheeler sectors.
Read more: Sona BLW Precision sees EVs driving growth, expands focus to robotics and physical AI
Citi said new products could help the company grow faster than the underlying industry. Its order book also improved to ₹25,100 crore from ₹24,000 crore at the end of the June quarter
However, it expects margins to remain under pressure due to sharp material cost inflation, higher freight rates and a shift in product mix towards lower-margin two-wheeler traction motors.
Bernstein: Overweight | Target price ₹850
Bernstein maintained its “Overweight” rating on the stock with a target price of ₹850, implying an upside of 9% from Monday’s closing price.
The global investment firm said the 35% revenue growth in the September quarter reflected several factors coming together, including traction motors gaining market share, a strong recovery in differential assemblies and the ramp-up of suspension motors in China.
Bernstein said the business was entering the second half of FY27 with a broader base of growth and more programs set to ramp up. It added that earnings did not necessarily require a return to historical peak margins as long as the revenue opportunity continued to expand.
However, management has retained its EBITDA margin framework of 23%-25%.
Kotak Institutional Equities: Sell | Target price ₹700
Kotak Institutional Equities maintained a “Sell” rating and a target price of ₹700, implying a near 11% downside from Monday’s close.
Kotak expects Sona BLW’s revenue growth to accelerate, driven by a recovery in the differential assembly business, strong momentum in traction motors and railways, and incremental opportunities in differential gears. It also identified Physical AI and BEV traction motors as medium-term growth opportunities.
Despite these growth drivers, Kotak said valuation remained expensive, thereby underpinning its “Sell” recommendation.
JPMorgan: Underweight | Target price ₹600
JPMorgan maintained its “Underweight” rating and a target price of ₹600, implying an approximately 23% downside from Monday’s closing price.
JPMorgan attributed the 129% growth in the battery electric vehicle revenue to the normalisation of differential assembly revenue in North America, traction motor growth in Indian two- and three-wheeler electric vehicles, and the ramp-up of suspension motors in China.
The firm raised its FY27-FY29 revenue growth forecasts by 9%-13% and EBITDA forecasts by 5%-10%. It expects this to support the company’s earnings per share to grow at a compound annual growth rate of 23% over FY26-FY29. However, JPMorgan said the stock was already trading at 47 times its FY28 price-to-earnings ratio.
Analyst recommendation and stock reaction
Among the 21 analysts who cover Sona BLW, 14 have a “buy” rating, four say “hold”, and three have a “sell” rating on the stock. The consensus estimate of price targets implies no returns from the current market price for the stock.
Among other recommendations, Investec has a “Buy” rating on the stock with a target price of ₹840, while UBS has a “Buy” rating with a target of ₹950. Nomura has a “Buy” rating with a target price of ₹948.67, and CLSA has an Accumulate rating with a target of ₹971.
Shares of the company rose as much as 9.9% to an intraday high of ₹858.95 on Tuesday and were trading 9.4% higher at ₹855.8. With this move, the stock has extended its year-to-date advance to 80%.