
Choksey said his focus remains on companies with strong fundamentals rather than chasing new ideas in a weak market. He expects investors to use sharp corrections to add to existing holdings where the underlying business outlook remains intact.
“We like companies which are basically influenced and attracted by the discretionary spending,” Choksey said, pointing to auto ancillaries and the high-end and ultra-luxury segments of real estate.
He also sees opportunities emerging in power and utility companies following the recent decline in stock prices. According to Choksey, the broader strategy is to remain selective and add to fundamentally strong companies when valuations become more attractive.
Despite the recent weakness, Choksey believes the market is approaching levels where buying support could emerge. He said the panic in the market has started to ease and expects the downside risk to be relatively limited from here.
Within the discretionary spending theme, Choksey highlighted Tata Elxsi and Tata Technologies as companies that have become more attractive.
He also likes Lotus Developers in the real estate space, particularly as demand for premium and luxury housing remains a focus.
Among auto companies, he said further corrections in stocks such as Bajaj Auto and Mahindra & Mahindra could create opportunities within the original equipment manufacturer (OEM) space.Cement demand remains firm despite margin concerns
Choksey also remains constructive on cement demand. He said demand has held up surprisingly well even during the monsoon season, with some regions continuing to report healthy offtake.
However, the margin outlook could differ from one company to another. Companies with better control over transportation costs and fuel expenses could be better positioned to protect profitability.
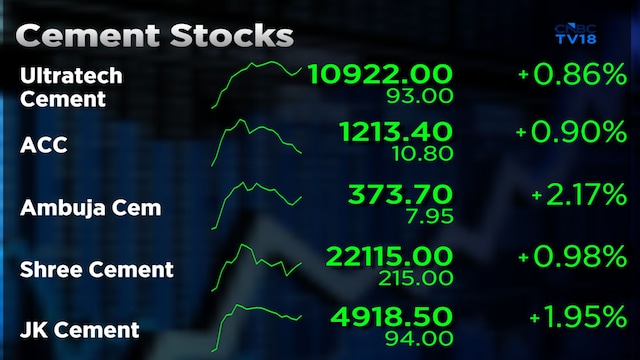
He specifically pointed to Ambuja Cements and ACC, both part of the Adani Group, as having advantages in transporting cement across their network. Alternative fuels could also provide some protection against higher costs.
Choksey said his preference in the sector remains with companies having a pan-India presence, particularly Adani Group’s cement businesses and UltraTech Cement.
On PB Fintech, Choksey said the stock had been trading at a premium valuation, leaving little room for negative developments.
The company’s potential move into insurance manufacturing could introduce a different set of challenges, he said, as underwriting insurance liabilities differs significantly from operating an asset-light distribution business.
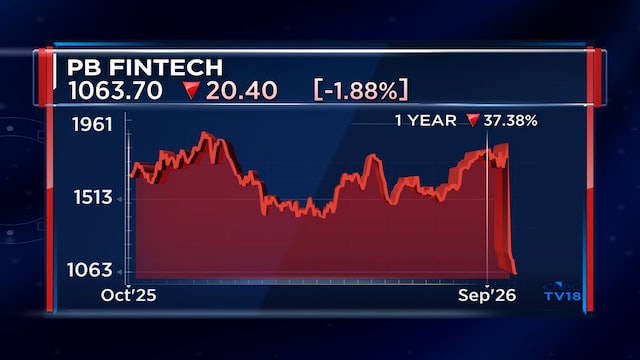
“Insurance remains a very deep pocket business,” Choksey said, adding that investors will have to wait and see how the company develops the new business model and whether it can generate meaningful profitability over the next few years.
Choksey was more positive on SBI Funds Management, saying the stock correction has created an opportunity for investors.
He said he likes the company’s overall business portfolio and believes the decline has largely been driven by the broader market weakness and selling pressure rather than a deterioration in the company’s fundamentals.
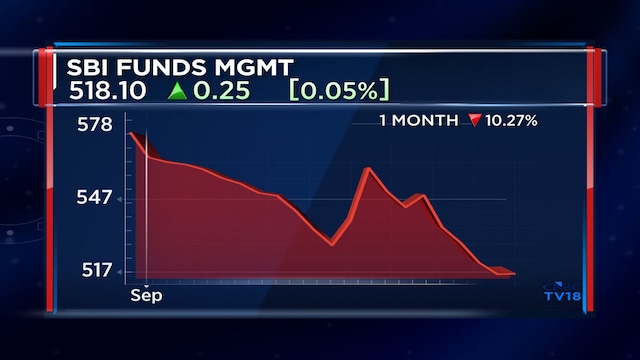
According to Choksey, companies such as SBI Funds Management can offer an accumulation opportunity when markets are under pressure, particularly when the underlying business remains fundamentally sound.
Watch video for more
