Filing an income tax return requires more than meeting the deadline. Here are five common mistakes taxpayers should watch out for, from missed income …
 1/5
1. Missing Filing Deadlines: Late filing triggers penalties and interest charges that grow the longer you wait. Even if you can’t pay in full, filing on time (or requesting an extension) avoids the steepest fees.
 2/5
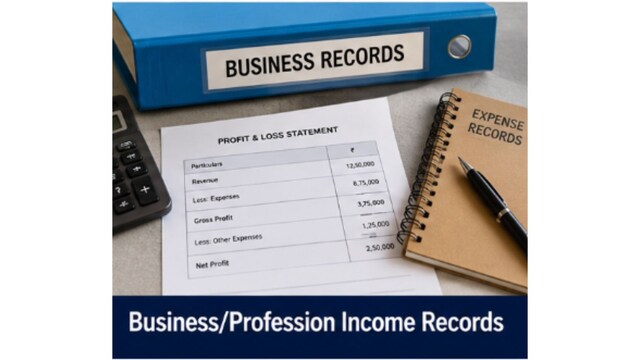
2. Ignoring Income Documents: Forgetting to report income from freelance work, investments, or side gigs is a common red flag. The tax authority often already has these records, so mismatches can trigger notices or audits.
 3/5
3. Overlooking eligible deductions: Many filers skip deductions or credits they qualify for, like education expenses, retirement contributions, or home office costs, simply because they don’t know to claim them.
 4/5
4. Incorrect Personal Information: Simple errors like a misspelled name, wrong Social Security/tax ID number, or outdated address can delay processing or cause a return to be rejected outright.
 5/5
5. Poor Record Keeping: Failing to save receipts, invoices, and supporting documents makes it hard to substantiate deductions if questioned later, and often leads to missed write-offs in the first place.