
Metal companies are likely to report mixed earnings in the July-September quarter (Q2FY27), with higher volumes supporting steel producers even as lower realisations and rising input costs put pressure on margins.
Ferrous metal companies could see sequential volume growth of around 15-25% in the second quarter, supported by capacity ramp-ups following maintenance shutdowns in the previous quarter.
However, steel realisations are expected to decline by around ₹500-1,300 per tonne, with long steel prices facing a sharper fall of nearly ₹3,500 per tonne.
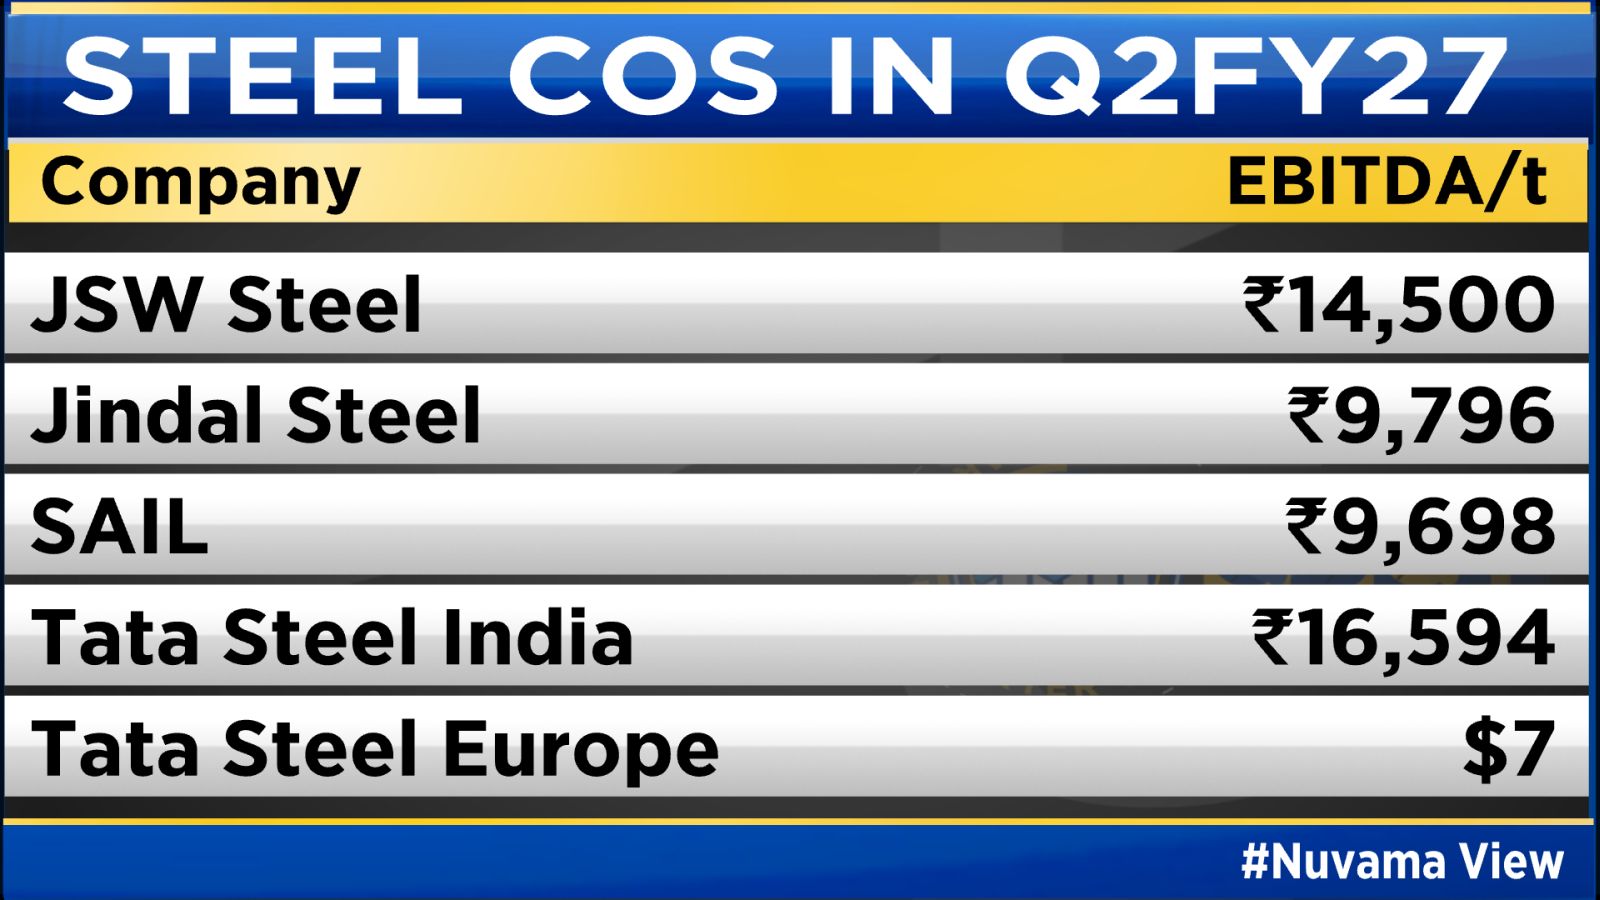
Higher coking coal costs, estimated to rise by around $10-15 per tonne, could add to the pressure, partly offset by lower iron ore costs. As a result, EBITDA per tonne is expected to decline by around ₹600-2,200 sequentially across steel companies. Jindal Steel could face the sharpest decline, while JSW Steel is expected to be relatively more resilient.
Despite the pressure on per-tonne profitability, absolute EBITDA for most steel companies is expected to increase by around 10-13%, supported by higher volumes. Tata Steel Europe is also expected to return to profit after reporting a loss in the first quarter.
The outlook for non-ferrous companies is mixed. Lower aluminium prices could lead to an estimated 8% decline in Hindalco’s India EBITDA, including Utkal Alumina, while Vedanta Aluminium’s EBITDA could fall by around 4%.
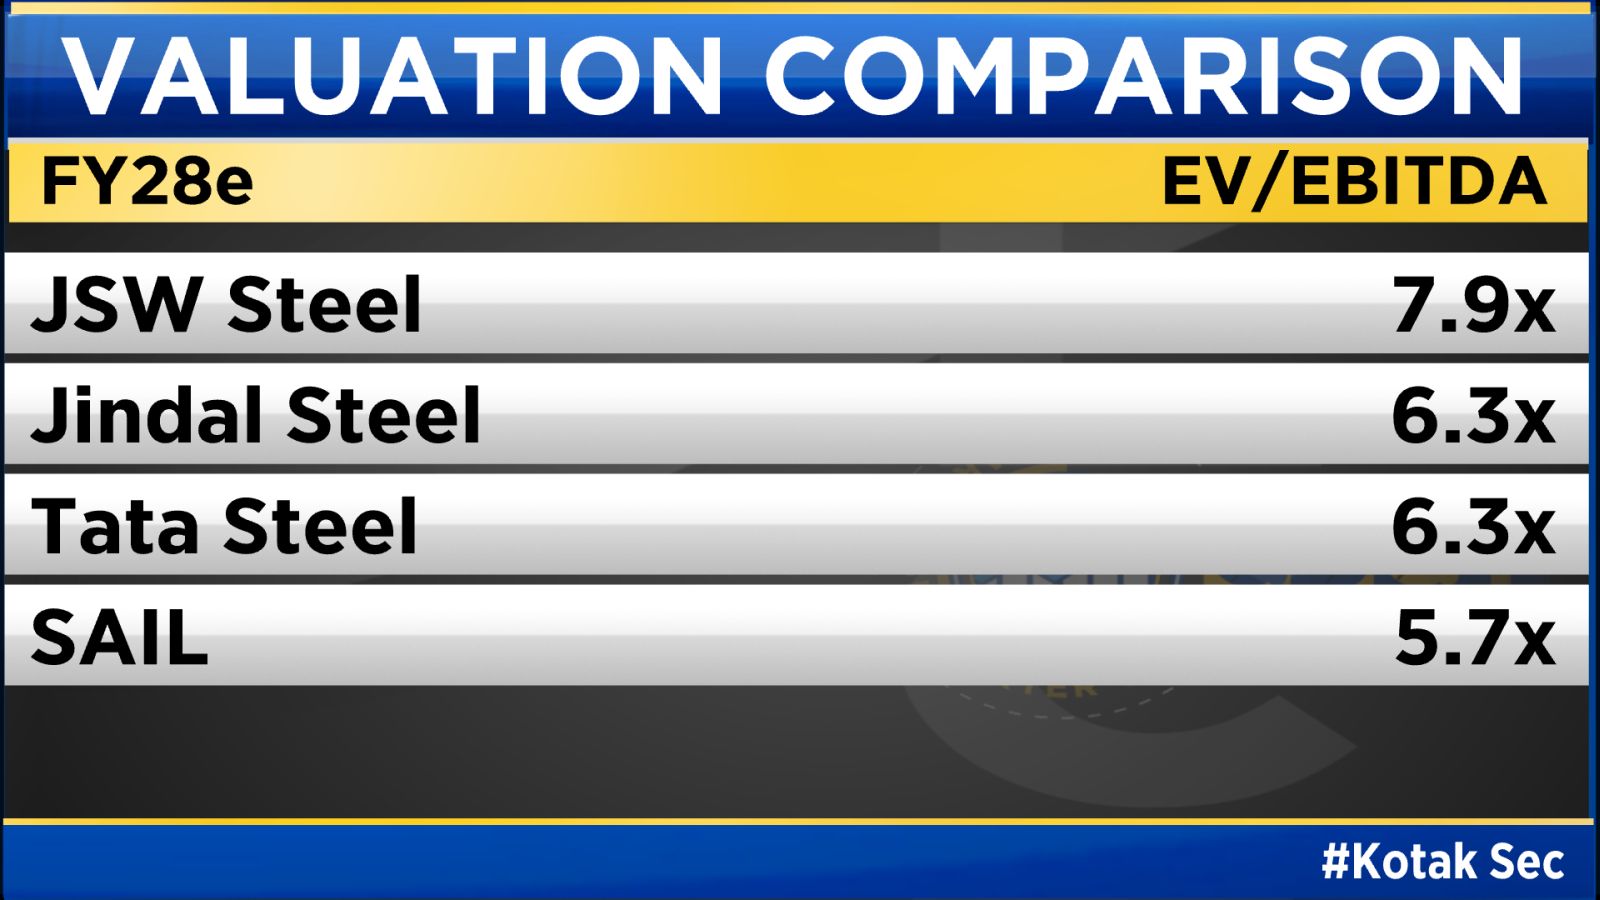
Novelis’ adjusted EBITDA is expected to remain broadly flat at around $500 million. In contrast, higher zinc prices could lift Hindustan Zinc’s EBITDA by around 5% and Vedanta’s by approximately 7%.
Against this backdrop, Pinakin Parekh, Director and Analyst at HSBC Securities and Capital Markets (India) Private Limited, remains positive on aluminium, citing the prospect of tight supply and demand growth outpacing capacity additions over the next few years.
“HSBC forecasts are still for aluminium to average close to $3,400- $3,500 for next year as well, and we expect prices to remain firm, “Parekh said, adding that the metal’s longer-term outlook remains supportive despite the recent correction in prices and stocks.
Aluminium prices had risen sharply amid supply disruptions in the Middle East, which pushed up both prices and premiums. However, expectations that some of these supply disruptions will ease, along with new capacity entering the market from next year, have moderated the outlook.
Even so, HSBC Securities expects the aluminium market to remain tight over the next few years, as demand growth is likely to exceed additional supply. This could support prices and earnings for Indian aluminium producers.
For the entire discussion, watch the accompanying video

Metals earnings outlook: HSBC Securities prefers aluminium, selective steel stocks
Catch all the stock market live updates here
NOTE TO READERS
Disclaimer: The views and investment tips expressed by investment experts on CNBCTV18.com are their own and not that of the website or its management. CNBCTV18.com advises users to check with certified experts before taking any investment decisions.