Motilal Oswal has initiated coverage with a “buy” rating and has set a target price of ₹180 per share.
The brokerage is of the view that Turtlemint Fintech Solutions is powering India’s insurance journey. It has built a scaled, technology-enabled insurance distribution franchise in the country. It has over 5.5 lakh certified point-of-sale persons (PoSPs) and a strong foothold in India’s insurance distribution, with over 75% of the premiums originating from the B30+ markets.
Motilal Oswal is of the view that India’s insurance penetration remains among the lowest globally against a government target of “insurance for all” by 2047. Assisted distribution drives 95% of retail insurance sales, underscoring the structural relevance of Turtlemint’s model.
The PoSP channel provides insurers a cost-effective means to expand distribution across India’s underserved regions, as evidenced by the 38% compound annual growth rate (CAGR) in PoSPs over FY20-25 compared to 9% for individual agents, it said.
Also, PoSP-driven premiums are growing at nearly twice the industry rate, Motilal Oswal said, adding that Turtlemint, with its presence across 19,186 pin codes, is well-positioned to capture that opportunity.
In FY25, Turtlemint held a 30% market share in PoSPs registered via brokers and 16% of total PoSPs in FY25. It is one app with multiple journeys for all financial needs of customers as it covers an end-to-end distributor journey with an additional mutual funds and credit products making the platform a one-stop hop for all financial needs of customers, the Motilal Oswal note said.
The brokerage said Turtlemint has a young distributor base, with 61% being below 35 years of age, and typically starts PoSP as a secondary income, but rising earnings drive greater engagement. The FY20 cohort earned 3.8 times its first-year payout by FY26, increasingly making it a primary source of income, the note added.
Motilal Oswal expects 1.3 lakh to 1.5 lakh partner additions annually, active DPs are poised to grow at a 24% CAGR over financial year 2026-2029, driven by Turtlemint’s training-led activation engine and strong power retention, it said.
The brokerage said that growth in active DPs combined with 12% ticket size CAGR should drive 38% CAGR with respect to platform premium over FY26-29. A broadly stable 27% take rate, supported by continued momentum in fresh business and rising renewals, should translate into 35% revenue CAGR over FY26-29.
Motilal Oswal said a fast-growing policy pool and compounding of renewal book should likely lead to renewal revenue contribution rising to 25% by FY29. Supported by higher profitability for renewals, service EBITDA margins should expand to 22% by FY29 from 13% in FY26.
The brokerage also expects corporate overheads to clock a 6% CAGR over FY26-29, resulting in an adjusted EBITDA breakeven in FY27 and margin expansion of 11% by FY29.
The brokerage said Turtlemint currently trades at 17 times its September 28 estimated enterprise value (EV)/EBITDA. Its target price is premised on September 2028 estimated EV/EBITDA of 20x.
The key risk is regulatory uncertainty around commission structures, partly offset by passing the impact through to distribution parnets, it iaid.
Apart from Motilal Oswal, Jefferies is the only other brokerage that has coverage on the stock with a “buy” recommendation as well.
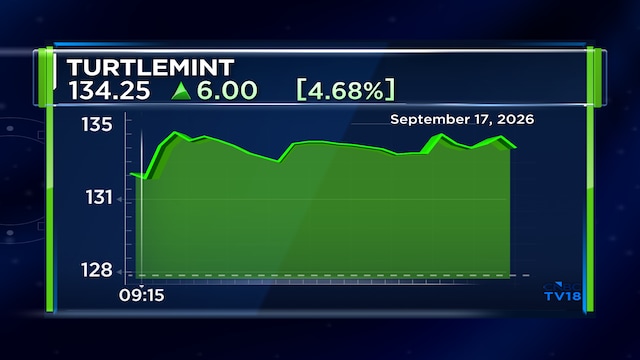
Shares of Turtlemint Fintech Solutions are trading 4.8% higher on Thursday at ₹133.8. The stock has declined 11% in the last one month and as a result has also turned negative on a year-to-date basis.
Also Read: Abu Dhabi Investment Authority among others issued shares in Neogen Chemicals’ ₹600 crore QIP