
For equities, Seth says the key factor to watch is when the slowdown in artificial intelligence (AI) capital expenditure becomes more meaningful. While overall AI spending is expected to continue, tighter financing conditions and growing political pushback around data centre implementation could affect the pace of spending, he says.
This is an edited transcript of the interview.
Q: What is your understanding of what’s happening in the bond markets and where it’s headed, and the implications?
A: Obviously, what you’re seeing is a repricing in the bond market, and it’s across the curve. You’ve seen the front-end pricing in now close to four hikes in the next 12 months, which is slightly higher than what I would expect.
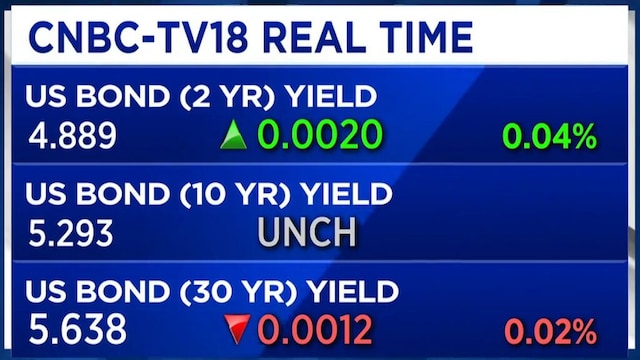
But obviously, the momentum is still in terms of the bond selling off, and then the term premium is going up. Combination of oil price, fiscal credibility, credibility issues, the issuance from the hyperscalers really crowding some of it out.
So, I do think overall, the bond markets are just repricing a high nominal growth rate and the rise in rates from the Fed in the coming quarters.
I do think it matters, but right now, looking at the earnings growth, it’s not maybe as much of a headwind. The financial conditions are still not very tight in the US despite the rate hike and where the bonds are at this point.
Two implications: one, the bonds or the fixed income has started to look attractive, specifically in the front end of the curve. So, if you are a long-term investor, you do want to be actually involved in front to belly, but I won’t go in the long end of the curve.
And then second, from the equity market perspective, at some point it will matter. In addition to just the bond yields, when do you start seeing the slowdown in the AI capex? And we are getting close to that in terms of the second derivative changing meaningfully for the AI capex, and that will matter for equities.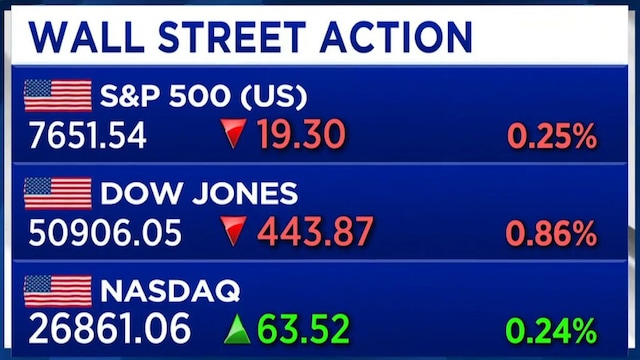
Q: Why do you think we are seeing some evidence or some signs that the AI capex is slowing down on account of this? You said second derivative. What do you think?
A: The overall AI spend is going to continue. There are two issues. One is obviously the cost of capital and the availability of financing is going to get tighter, specifically as you go down the credit curve. For hyperscalers, it’s probably not as big a deal or problem to borrow. But when you go down the credit curve, I think it’s getting tighter.
The second is in terms of the actual implementation of data centers, you’re seeing a bit more of a pushback and noise from a political standpoint. And we are getting close to the midterm elections.
Watch the full conversation here

I do think the outcome of the midterm is going to be extremely important to watch in terms of what the overall public opinion is, and AI is becoming the centre of the debate at this point in the US.
Catch all the latest updates from the stock market here